2026-10-31 13:20

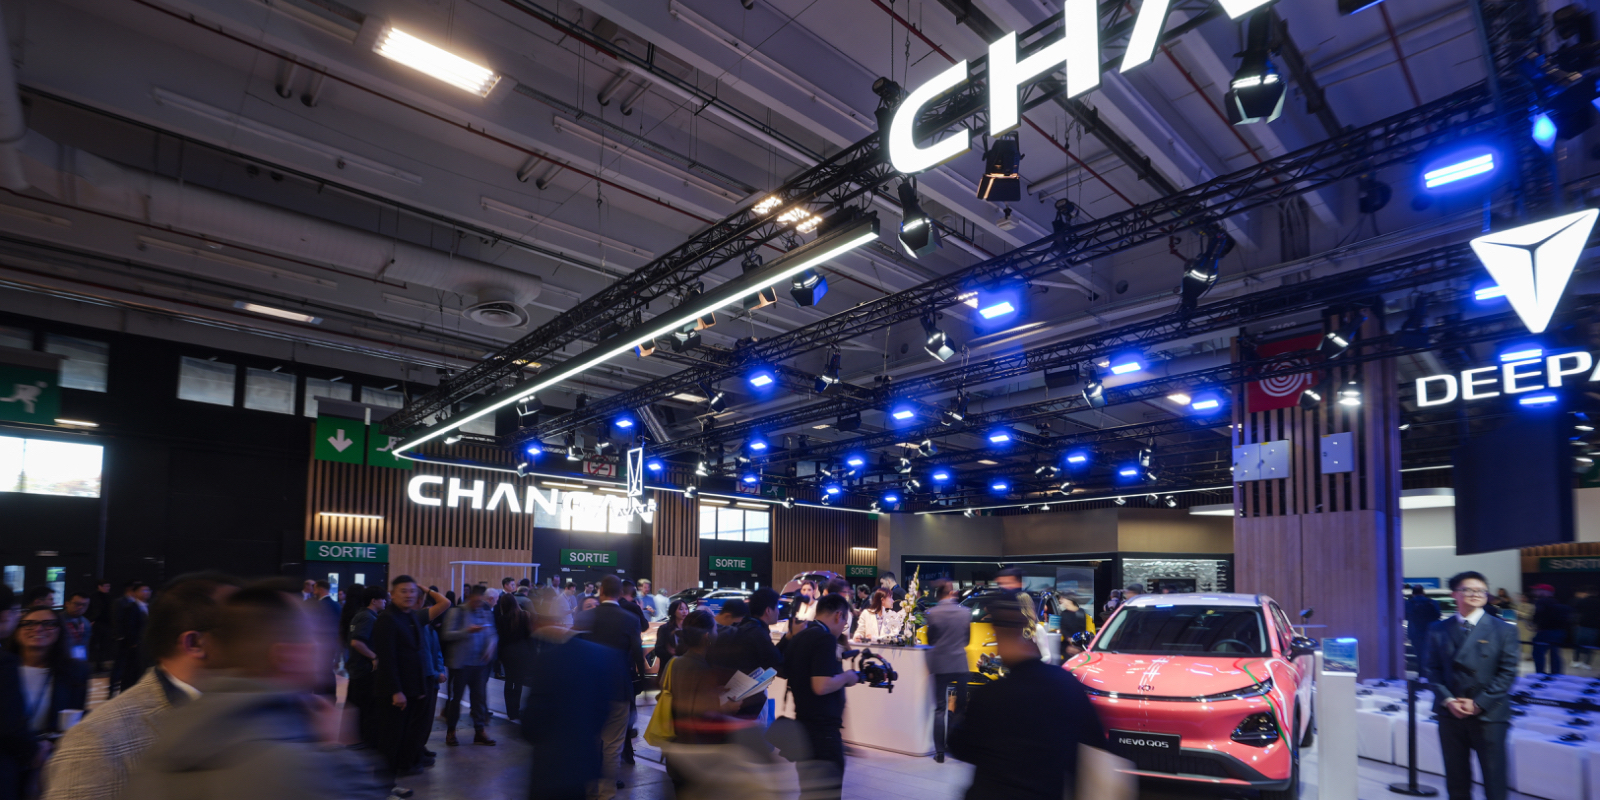
On October 31st, Changan Automobile (000625. SZ) released its 2026 third quarter report. Looking at the surface data alone, this financial report is difficult to make people relaxed: in the first three quarters, the operating revenue was 101.88 billion yuan, and the net profit attributable to the parent company was 59.275 million yuan. In the third quarter, there was even a net loss attributable to the parent company of 758 million yuan.
The reasons for the decline in profits are not complicated. The financial report clearly states that the main influencing factors are a decrease in sales, an increase in raw material prices, and an increase in exchange losses. The impact of exchange losses is particularly evident, with financial expenses increasing from -2.065 billion yuan in the same period last year to 647 million yuan this year, with fluctuations of over 2.7 billion yuan directly pressing on the income statement.
If we only look at profits, this is a worrying financial report. But the response of the capital market is not so pessimistic, and the stock price of Changan Automobile has not fluctuated significantly. The reason is that the short-term pressure on the income statement masks the substantial changes in Changan Automobile's "quantity, price, and profit" structure. Overseas sales are on the rise, the new energy structure is improving, and high-value vehicle models are on the rise. These long-term indicators are moving in the right direction. What this company is going through is not a recession, but the financial pain it must endure during the transition period.
The changes in quantity, price, and profit are more worth watching than the profit and loss statement
The numbers on the income statement are the results, but what determines the future direction of this result are changes in sales structure, bicycle prices, and sources of profit. What is truly worth looking at in Chang'an's third quarter report is not how much net profit has fallen, but where these three variables are heading.
Let's first look at the 'quantity'. Overseas has become the largest increment, and new energy has firmly established itself in the million dollar tier. In the first three quarters, Changan Automobile sold 727000 vehicles overseas, a year-on-year increase of 56%, accounting for 43% of the overall sales volume; In the third quarter, overseas sales reached 270000 units, a year-on-year increase of 64.3%, setting a new historical high for the quarter. The average price of bicycles in overseas markets is higher than that in China, and the profit margin is also larger.
At present, Changan has 62 products on sale overseas, with over 1300 channels, business coverage in 149 countries and regions, and an overseas production capacity of 450000 vehicles. The sales increment brought by the systematic layout is becoming apparent, and overseas sales in the third quarter maintained year-on-year growth. With the continuous increase in overseas market volume, its driving force on the overall profit structure will become stronger.
In the new energy sector, both Qiyuan and Shenlan have achieved the milestone of one million vehicles, which means that Changan has sufficient ownership in the new energy track to support the after-sales system, charging ecology, and second-hand car residual value management. These implicit capabilities are precisely the key to whether the brand can go far.
After reading the quantity, let's look at the "price". The proportion of high-value products has increased, and users are willing to pay for high-end and intelligent driving. In the first three quarters of new energy products, the average price of overseas bicycles is on the rise. Among them, the average price of bicycles in Chang'an Qiyuan increased by 12000 yuan year-on-year, and the average price of bicycles in Avita increased by 2000 yuan year-on-year. The Changan Qiyuan Q06 is a sample for observing changes in Changan's price structure. Pure electric models with a range of 700 kilometers account for over 85%, and users who choose to use the Tianshu Navigation Ultra model account for 45%.
This indicates that users are not looking for low prices, but for high-end and intelligent driving. In an SUV market ranging from 100000 to 150000 yuan, users are willing to pay extra for advanced intelligent driving and comfort features, which itself is a signal of brand improvement.
Finally, let's take a look at "profit": the sources of profit are changing, with an increase in overseas profits and a year-on-year decrease in losses for new energy. Although overall profits are under pressure, overseas business profits have increased year-on-year, while the new energy sector has reduced losses year-on-year. This quarter, Qiyuan significantly reduced its losses and achieved a single quarter profit in Q2, while Avita also achieved a year-on-year reduction in losses. Contract liabilities increased by 39.11% compared to the end of the previous year, corresponding to an increase in advance receipts, leaving room for subsequent revenue recognition. In the environment of ongoing price wars and fluctuating raw material costs, the improvement of these lines can better reflect the true direction of Changan's business quality than the total profit figures.
The three major plans enter the verifiable period from the investment phase
The short-term fluctuations on the income statement are the result. What truly determines the direction of Chang'an in the coming years is whether the three major plans can move from the "spending stage" to the "submission stage".
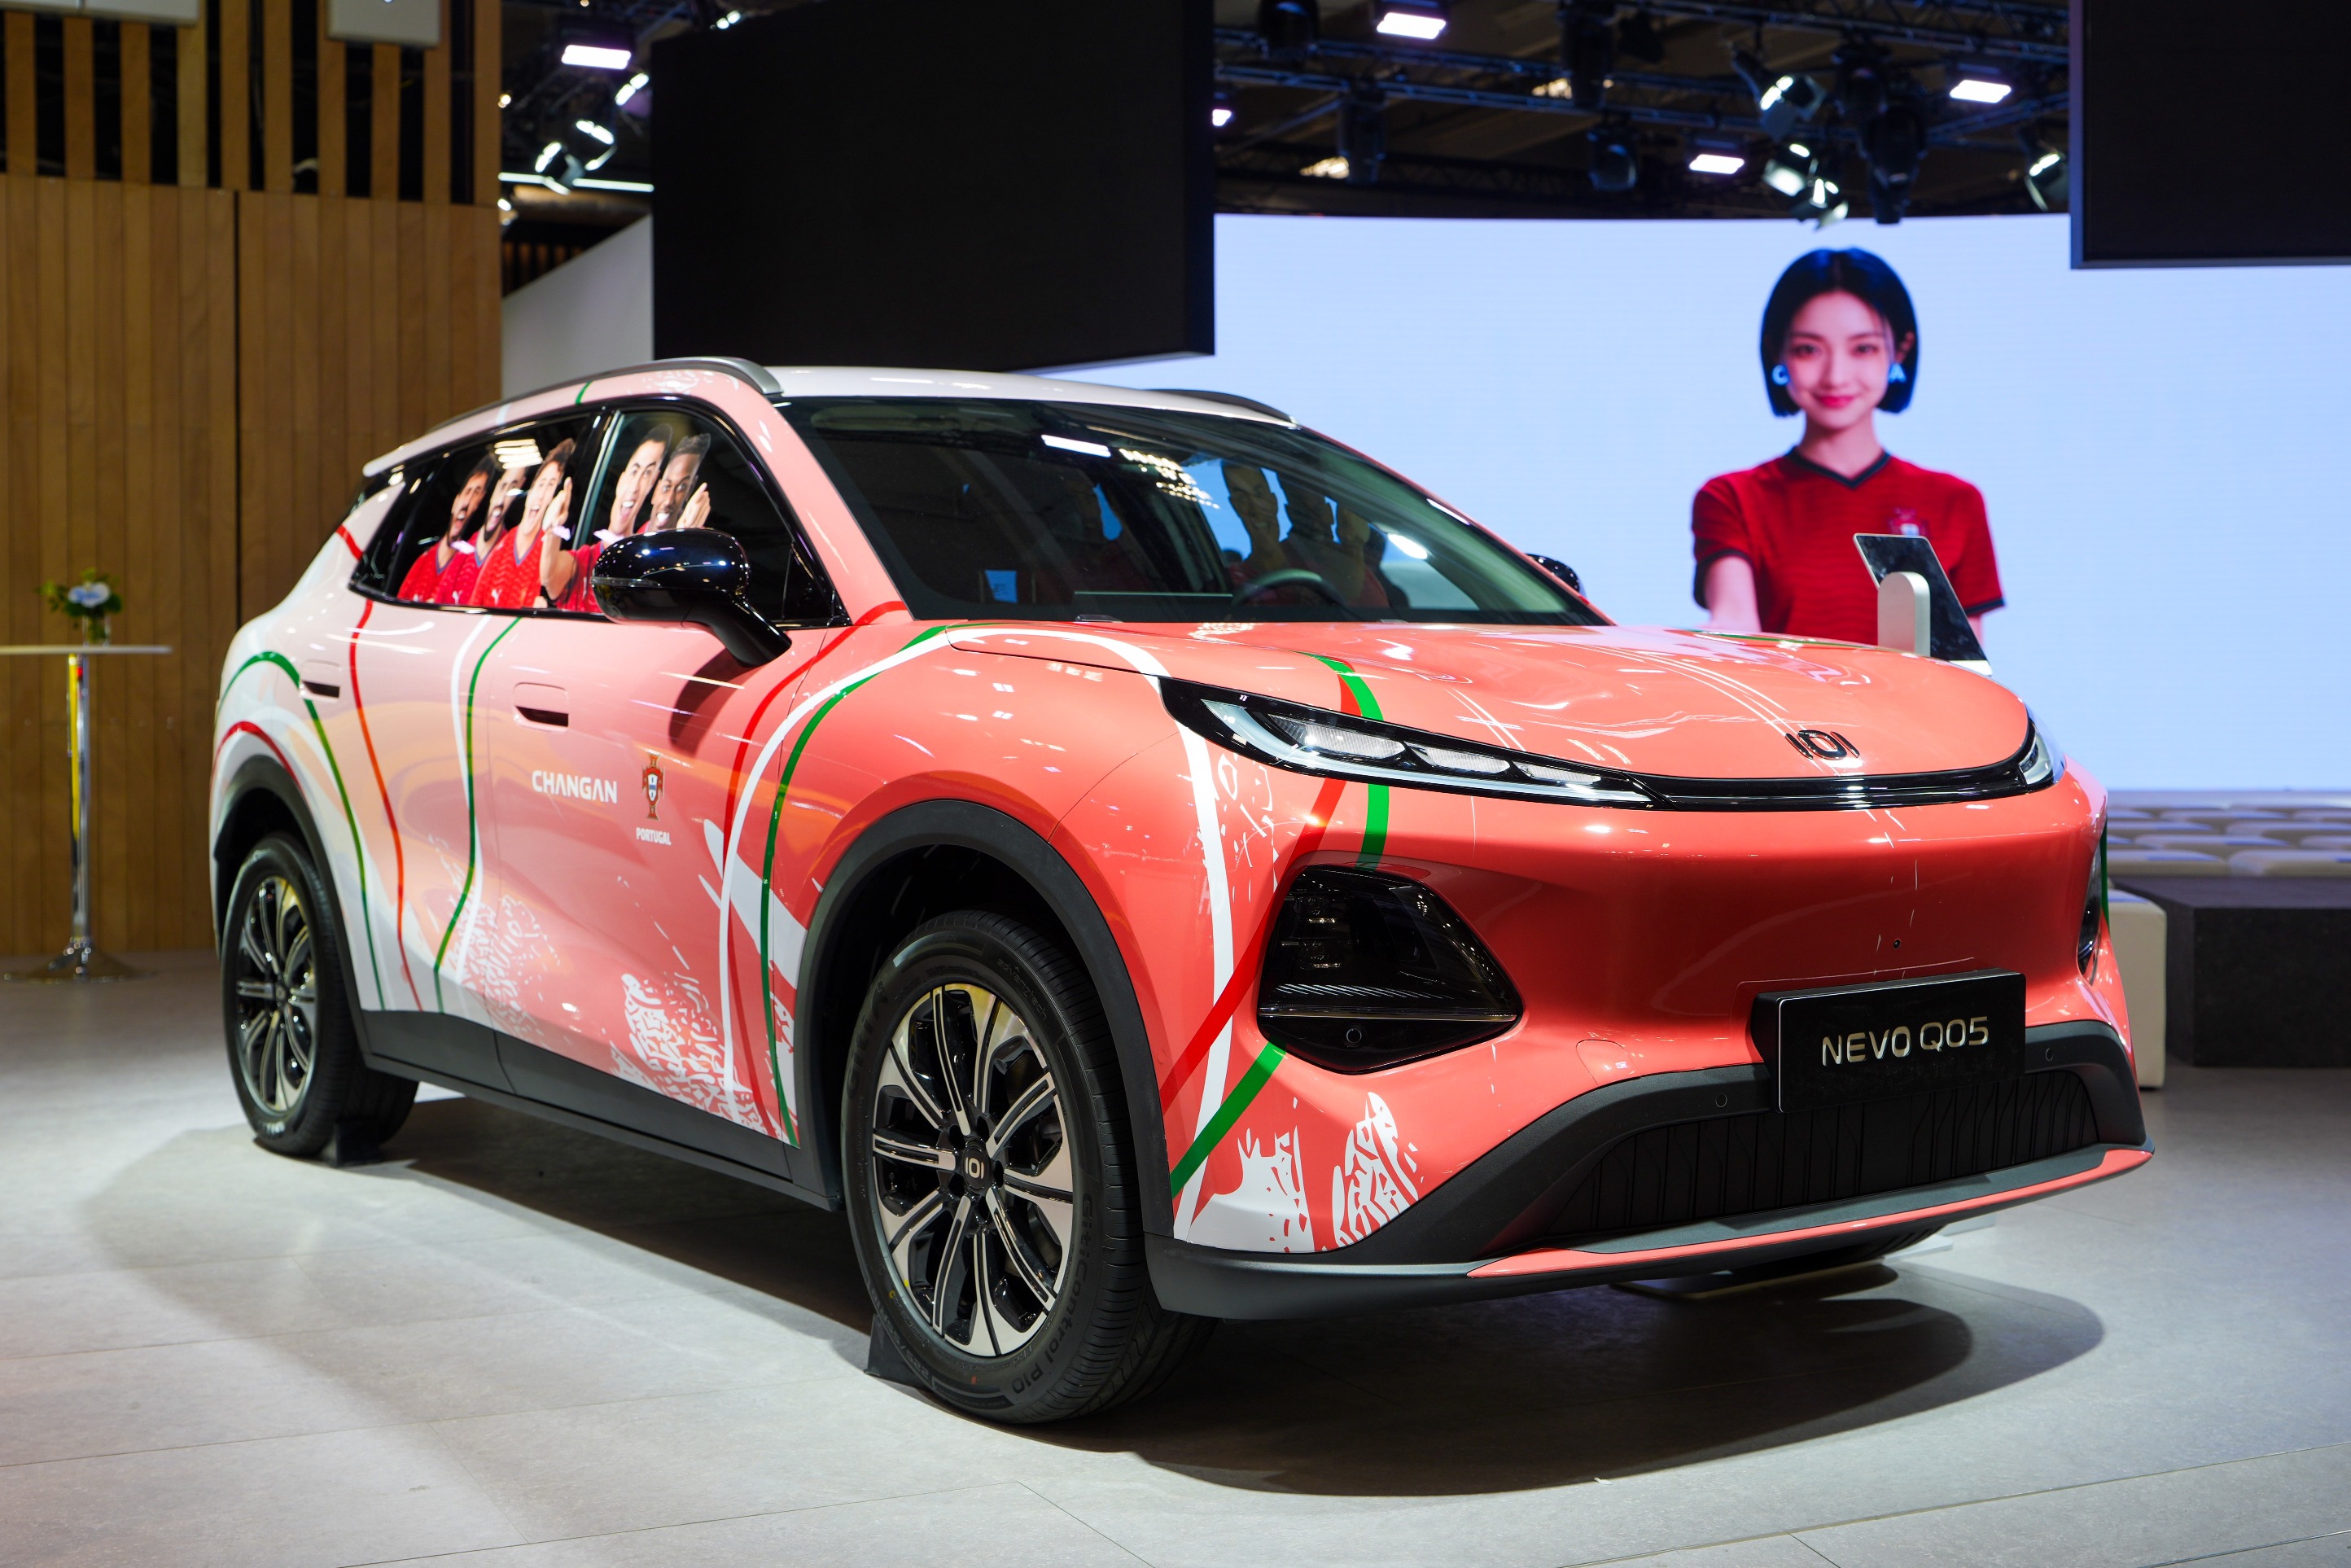
The new energy "Shangri La" plan has entered the product structure verification period. The global monthly average sales of the Deep Blue S05 have remained stable at over 15000 units, while the Qiyuan Q05 has won the sales championship for pure electric compact SUVs for seven consecutive months. These two major products have already achieved a stable scale rhythm.
More importantly, the improvement of product structure - Changan revealed that the platform where Qiyuan A06 and Q06 are located has already achieved profitability, and the marginal cost of new models on the same platform will be further reduced in the future. Although the new energy sector as a whole has not yet turned losses around, the trend of reducing losses is real. After increasing the scale, the bargaining power of the supply chain and the ability to dilute research and development costs will also follow suit. The turning point of profitability for Changan New Energy may be closer than market expectations.
The intelligent "Beidou Tianzhu" plan has entered the period of mass production and monetization. The Chang'an Tianshu Navigation Intelligent Driving Assistance System is the first end-to-end intelligent driving assistance solution independently developed by a central enterprise. The underlying system adopts a central ring network communication architecture and dual redundancy design, with seven core systems designed with dual redundancy according to three-level requirements. The middle layer is a segmented end-to-end big model that combines the VLA big model with the world model, while the top layer is a fully stack self-developed algorithm system and natural language interaction that can understand and learn preferences.At the level of security algorithm, more than 400000 simulation runs covered extreme scenarios such as tire burst, rainstorm, oncoming vehicles on narrow mountain roads, sudden bright light at tunnel exits, malicious congestion, etc. The optional rate of the Tian Shu Navigation Ultra version is close to 50%, which means that users truly recognize this system, and the path of technology monetization has been completed. Once technology assets are reused on a large scale, the gap between Changan and competitors will continue to widen in the increasingly homogeneous competition of intelligent driving.
The globalization plan of "embracing all rivers" has entered a period of systematic implementation. Products, channels, markets, and production capacity are being promoted simultaneously. The Rayong factory in Thailand is Changan's first overseas new energy vehicle base, with an annual production capacity of 100000 vehicles in the first phase. This factory not only supplies to Thailand, but also ships the Shenlan S05 and Qiyuan Q05 to 18 right-hand drive countries such as Indonesia, Singapore, and Australia after they are produced. The factory's 20000th vehicle was produced in June this year. Around the factory, 10 core suppliers have been brought to Thailand by Changan Automobile to build factories, and more than 40 local Thai component companies have entered the supporting circle.
In terms of standards, the Deep Blue S05 and S07 have undergone adaptive development for the European market, and both cars have received a five-star safety rating from the European NCAP. The service system is synchronously implemented, and European users enjoy a 7-year or 160000 kilometer vehicle warranty, an 8-year or 200000 kilometer electric drive component warranty, and a 3-year free pan European road rescue. Spare parts are delivered within 1 day to major cities and equipped with a 24-hour European call center.
From Thailand's right-hand drive manufacturing hub to Europe's safety certification and product import, Changan's overseas expansion is not about selling cars, but about moving production capacity, supply chain, and certification system to the local market. Overseas markets are becoming the ballast for hedging against domestic fluctuations.
Hot selling products relay and fuel base support industry transformation period
The verification of the three major plans will ultimately fall into specific products and financial statements. When the industry is in a deep water zone of new and old kinetic energy conversion, Changan has adopted a "dual line battle" strategy: using the explosive lineup of new energy brands to grab future increments, and using the basic performance of fuel vehicles to support current investment.
The three brands of Qiyuan, Shenlan, and Avita have not only covered the price range from 100000 to 500000 yuan, but have also established a product lineup in terms of popular products.
Qiyuan is responsible for the volume building task in the mainstream home market. Within 24 hours of its launch, Qiyuan Q06 had orders exceeding 35000 units and delivered over 10000 units in the first month, making it the current hot selling product; The Qiyuan Q05 continues to rank among the top in the compact pure electric SUV segment market and is a stable base for the segment market. These data indicate that Qiyuan has found its own rhythm.
Deep Blue undertakes the scale task of mid to high end new energy. The global monthly average sales of Deep Blue S05 remain stable at over 15000 units, supporting overseas scale up; The Deep Blue S07 is aimed at the European market with PHEV and EV dual power, opening up the second curve of new energy exports.
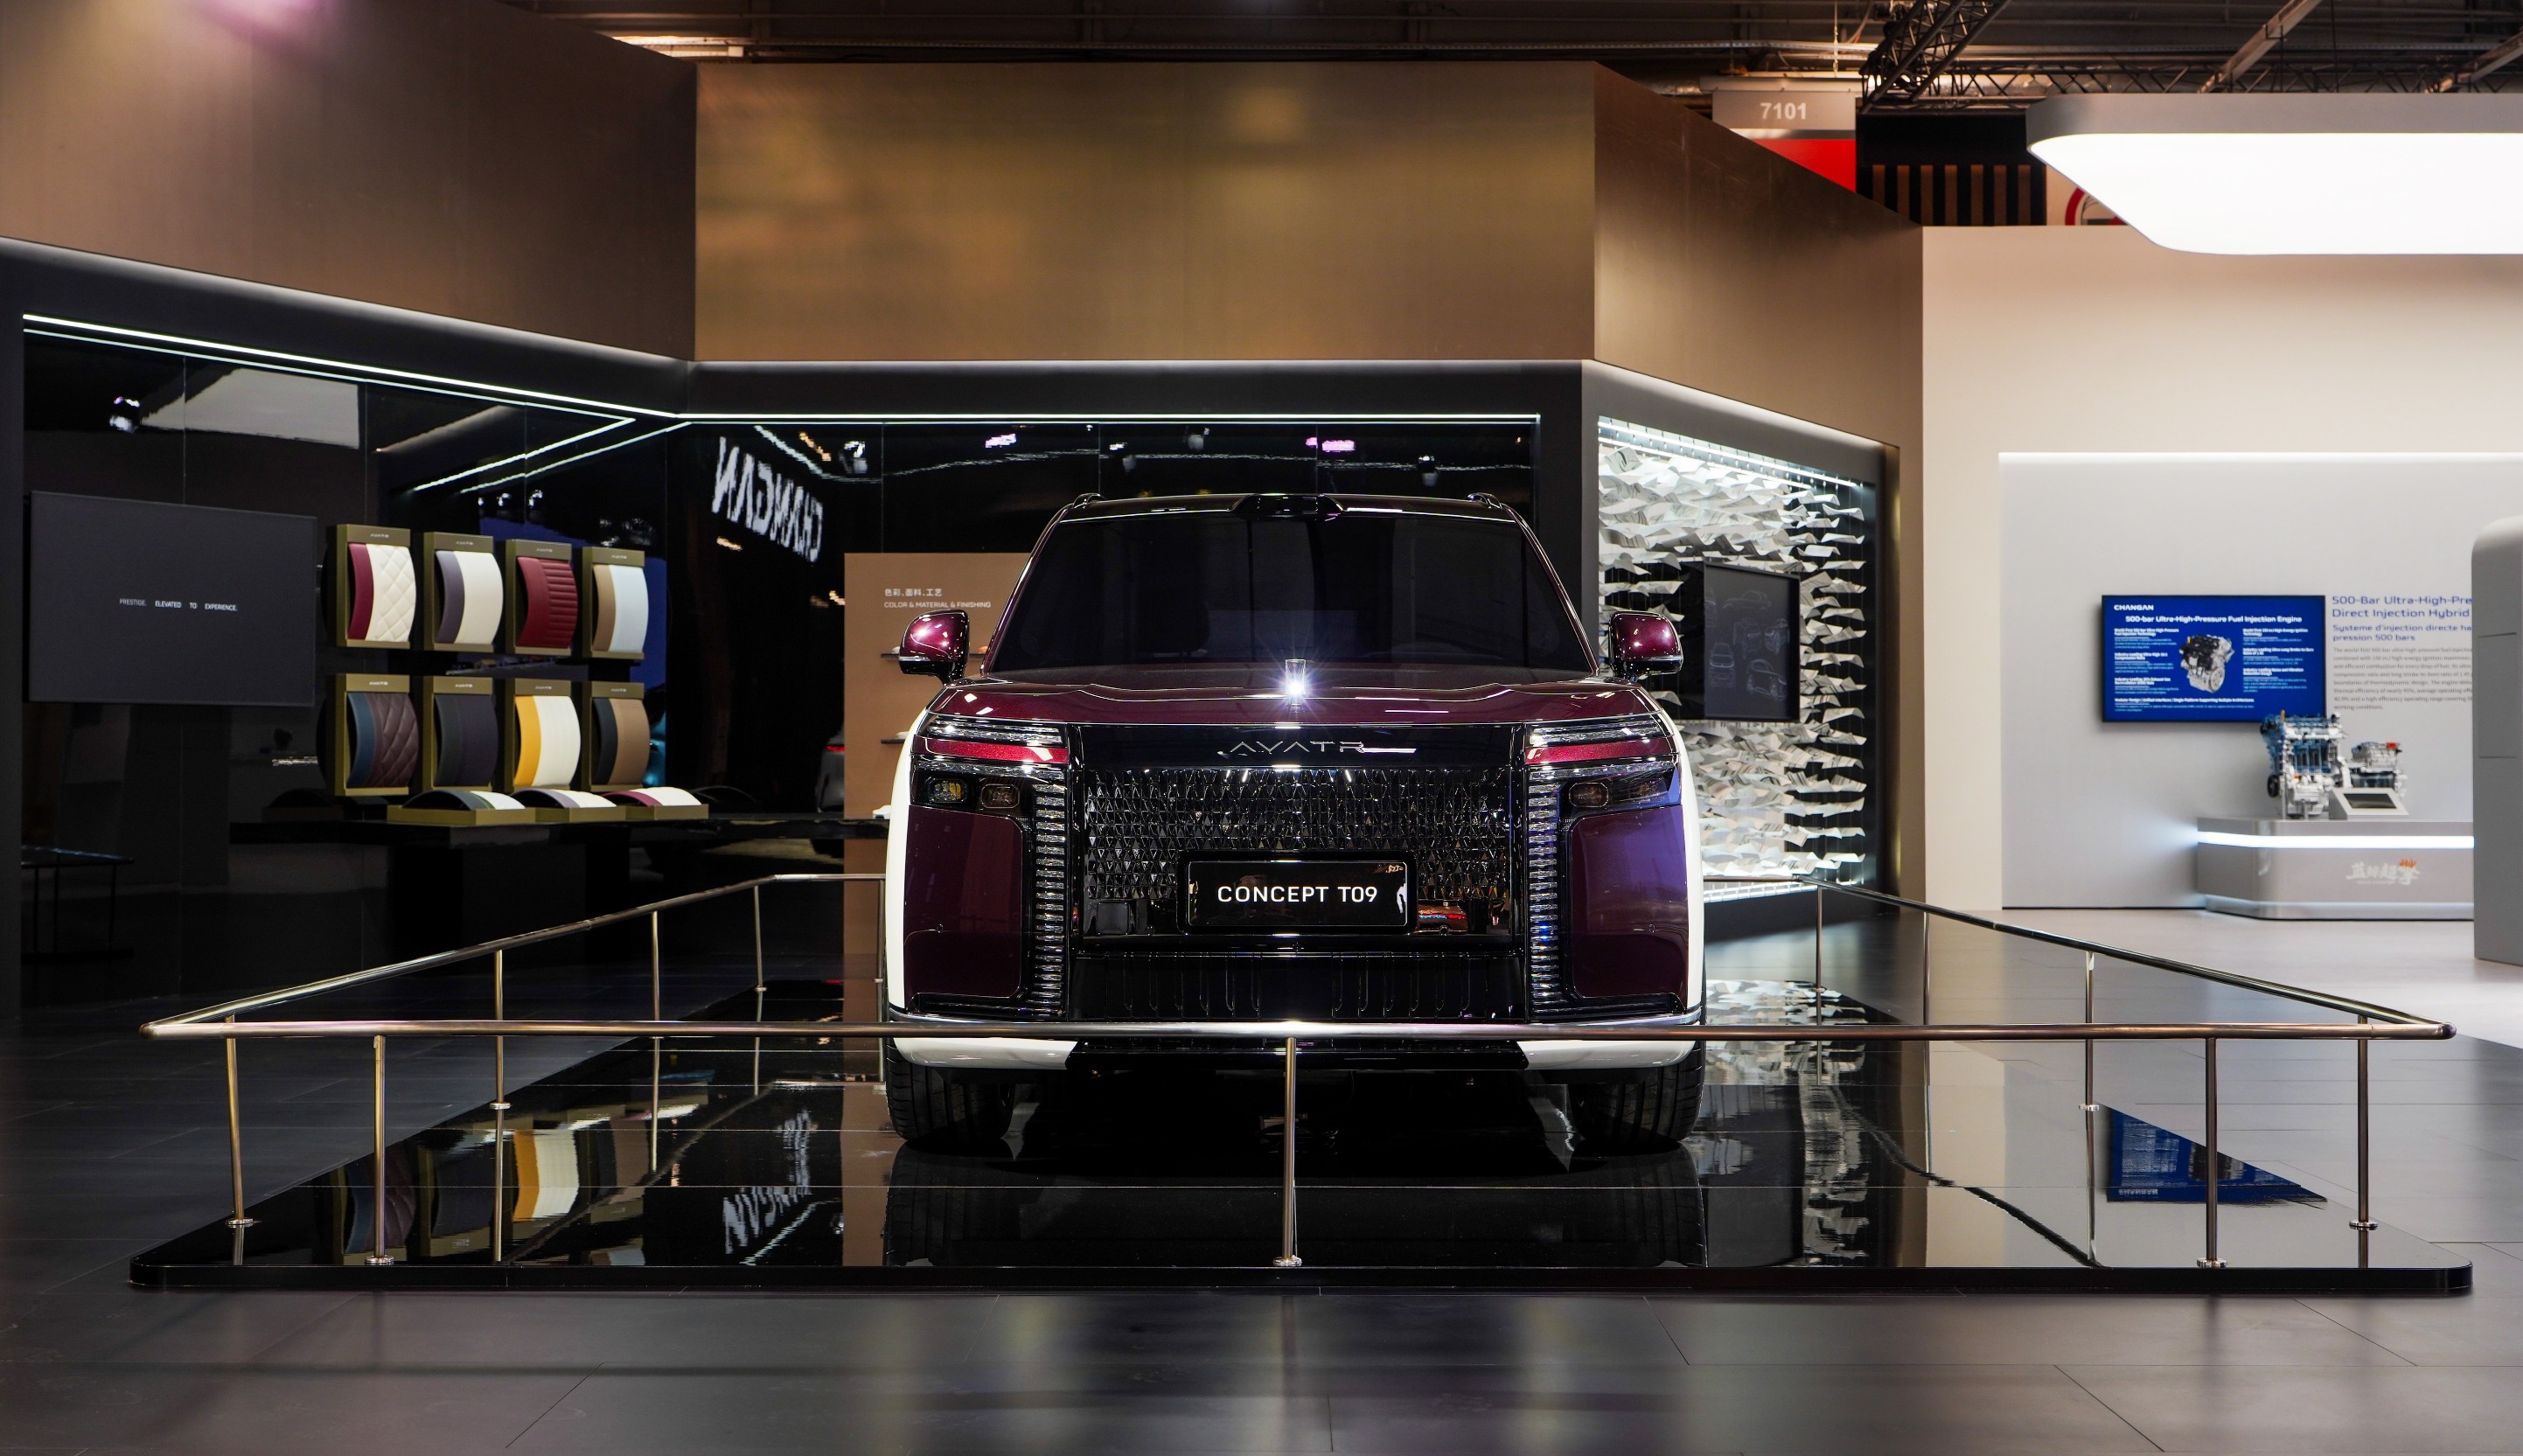
Avita undertakes the task of brand advancement, with the Avita T09 making its global debut in Paris and anchoring itself in the 500000 yuan flagship luxury SUV market. T09 combines the technological capabilities of Changan, Huawei, and CATL, equipped with Huawei Qiankun Intelligent Driving and Taihang Intelligent Control technologies, a 2.0T hybrid engine and a three motor distributed electric drive, with a total system power of over 1000 horsepower. Paired with a 71.24 kWh CATL Snapdragon Remote Battery, the CLTC pure electric range can reach up to 400 kilometers, pushing Changan's product boundaries to the high-end.
In the fuel vehicle sector, the Blue Whale hybrid engine continues to iterate, CS75PLUS、 The IP of these large products of Yidong is still being upgraded, and the basic structure of Changan Automobile's fuel vehicles is still relatively stable. At the stage where the penetration rate of new energy has not fully covered all segmented markets, nearly half of the sales of fuel vehicles bear the cash flow task of supporting research and development investment and channel operation.
Looking at it from a broader perspective, the profit pressure that Changan Automobile is currently facing is a price that must be paid during the transition period. Exchange losses, raw material price increases, and short-term fluctuations caused by changes in sales structure will also exist. But the management of Chang'an did not avoid short-term difficulties in the financial report, nor did they use empty long-term narratives to cover up problems.
Returning to this third quarter report, the profit figures reflect the common pressure of the industry cycle. The profit pressure that Changan Automobile is currently facing is also the price that must be paid during the transformation period, which all enterprises must face. The management of Chang'an did not avoid short-term difficulties in the financial report, nor did they use empty long-term narratives to cover up problems.
Because structural changes reflect Changan's own progress, the three major plans have reached the stage of submission, the basic cash flow of fuel vehicles has stabilized, and three brand tiers have formed. Meanwhile, verifiable signals have emerged in the overseas systematization, new energy single product, and intelligent monetization lines, indicating that the investment in transformation in the past few years has entered a stage of being tested by the market. The fluctuation of short-term financial statements does not change this judgment. With the recovery of Changan Automobile's payment rhythm in the fourth quarter, the cash flow situation for the whole year is likely to improve.