Economic Observer Follow
2026-11-03 18:54

On November 2nd, Mr. Zhang, who had just received his salary from last month, habitually opened Tencent Wealth Management to buy some wealth management products.
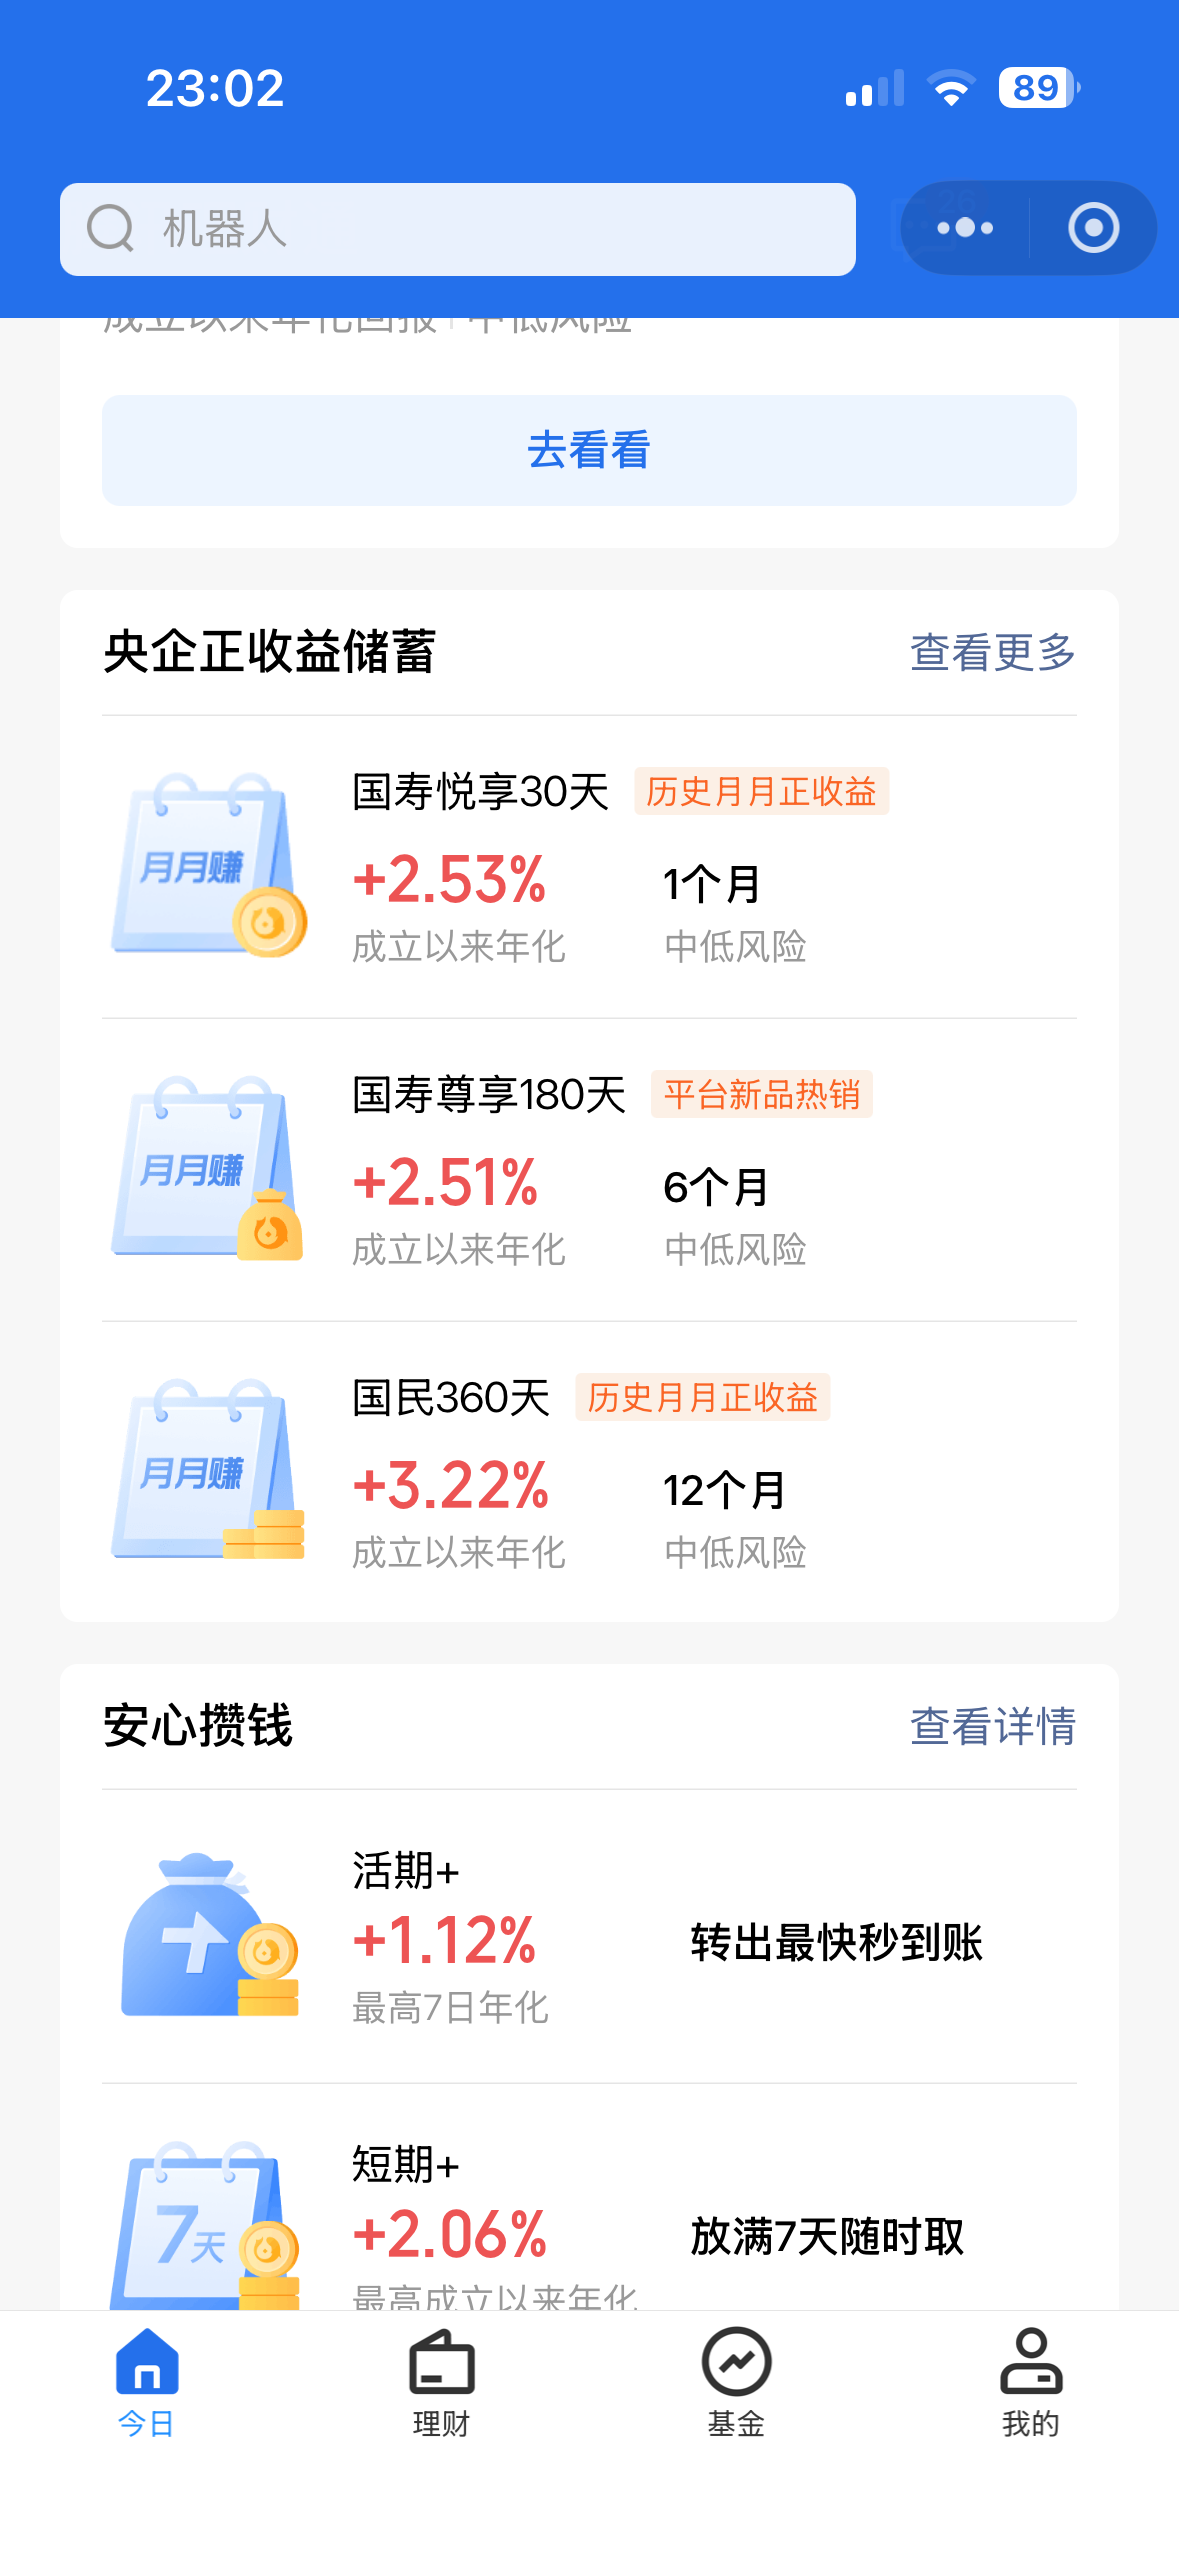
On the homepage of the Wealth Management Platform that Mr. Zhang saw, the words "Central Enterprise Positive Income Savings" attracted him. Clicking on 'View More', Mr. Zhang found himself entering the savings insurance page, which listed several commercial pension products launched by pension insurance companies.
Mr. Zhang felt a little puzzled: Do commercial pension products belong to savings? What is the difference between it and other insurance products?
With this question in mind, the Economic Observer reporter also clicked on the "Central Enterprise Positive Income Savings" tag section in the Wealth Management Channel. On the page, products such as "Guoshou Yuexiang 30 Days", "National 360 Days", and "Human Warm Heart 180 Days" are arranged in sequence, labeled with "Historical Monthly Positive Returns" or "Historical Period Positive Returns", and marked with annualized numbers ranging from "+2.39% to+2.68%" since their establishment. The risk level is displayed as "medium low risk", and the minimum purchase threshold is 100 yuan.
Taking "Guoshou Yuexiang 30 Days" as an example, its full registered name is "Guoshou Pension Anxin Yuexiang (Type B) Commercial Pension Product" (Guoshou Pension [2022] Commercial Pension No. 004), and the product terms clearly state that the insurance liability of this contract is to pay pension insurance benefits and death insurance benefits, with each payment being held for a period of 30 days.
This means that investors see insurance products in the "Central Enterprise Positive Income Savings" tag section. Commercial pension products refer to commercial pension insurance operated by pension insurance companies, which have functions such as pension fund management and risk protection, adopt independent account management, and are divided into standardized units. Commercial pension products are divided into four categories: liquidity management products, fixed income products, equity products, and hybrid products. Depending on the issuance purpose and management method, they also include specific products such as target date type and term guaranteed type.
The reporter called the customer service of Licaitong for inquiry, and the customer service stated that this type of product belongs to savings insurance, similar to bank wealth management, and cannot guarantee principal and interest.
In the "Frequently Asked Questions" section of the "Central Enterprise Positive Income Savings" tab on Wealth Management, there is a question and answer about "What is savings insurance". According to the explanation of Wealth Management, Wealth Management Savings Insurance "includes a variety of savings and wealth management insurance products produced by central state-owned enterprises such as China Life Insurance, PICC, China Taiping, and National Pension Insurance, as well as well-known insurance companies".
According to Article 8 of the "Measures for the Administration of Online Marketing of Financial Products" (hereinafter referred to as the "Measures"), which will officially come into effect on September 30, 2026, the content of online marketing should be based on the financial product contract. If it involves key information such as product name, product provider and seller name, product category, interest rate, risk warning, etc., it should be consistent with the relevant clauses of the financial product contract and displayed in a clear and conspicuous manner, without significant omissions, deliberate concealment or misleading.
A person working for a pension insurance company told reporters that insurance companies will not promote insurance products as savings, which is a regulatory red line.
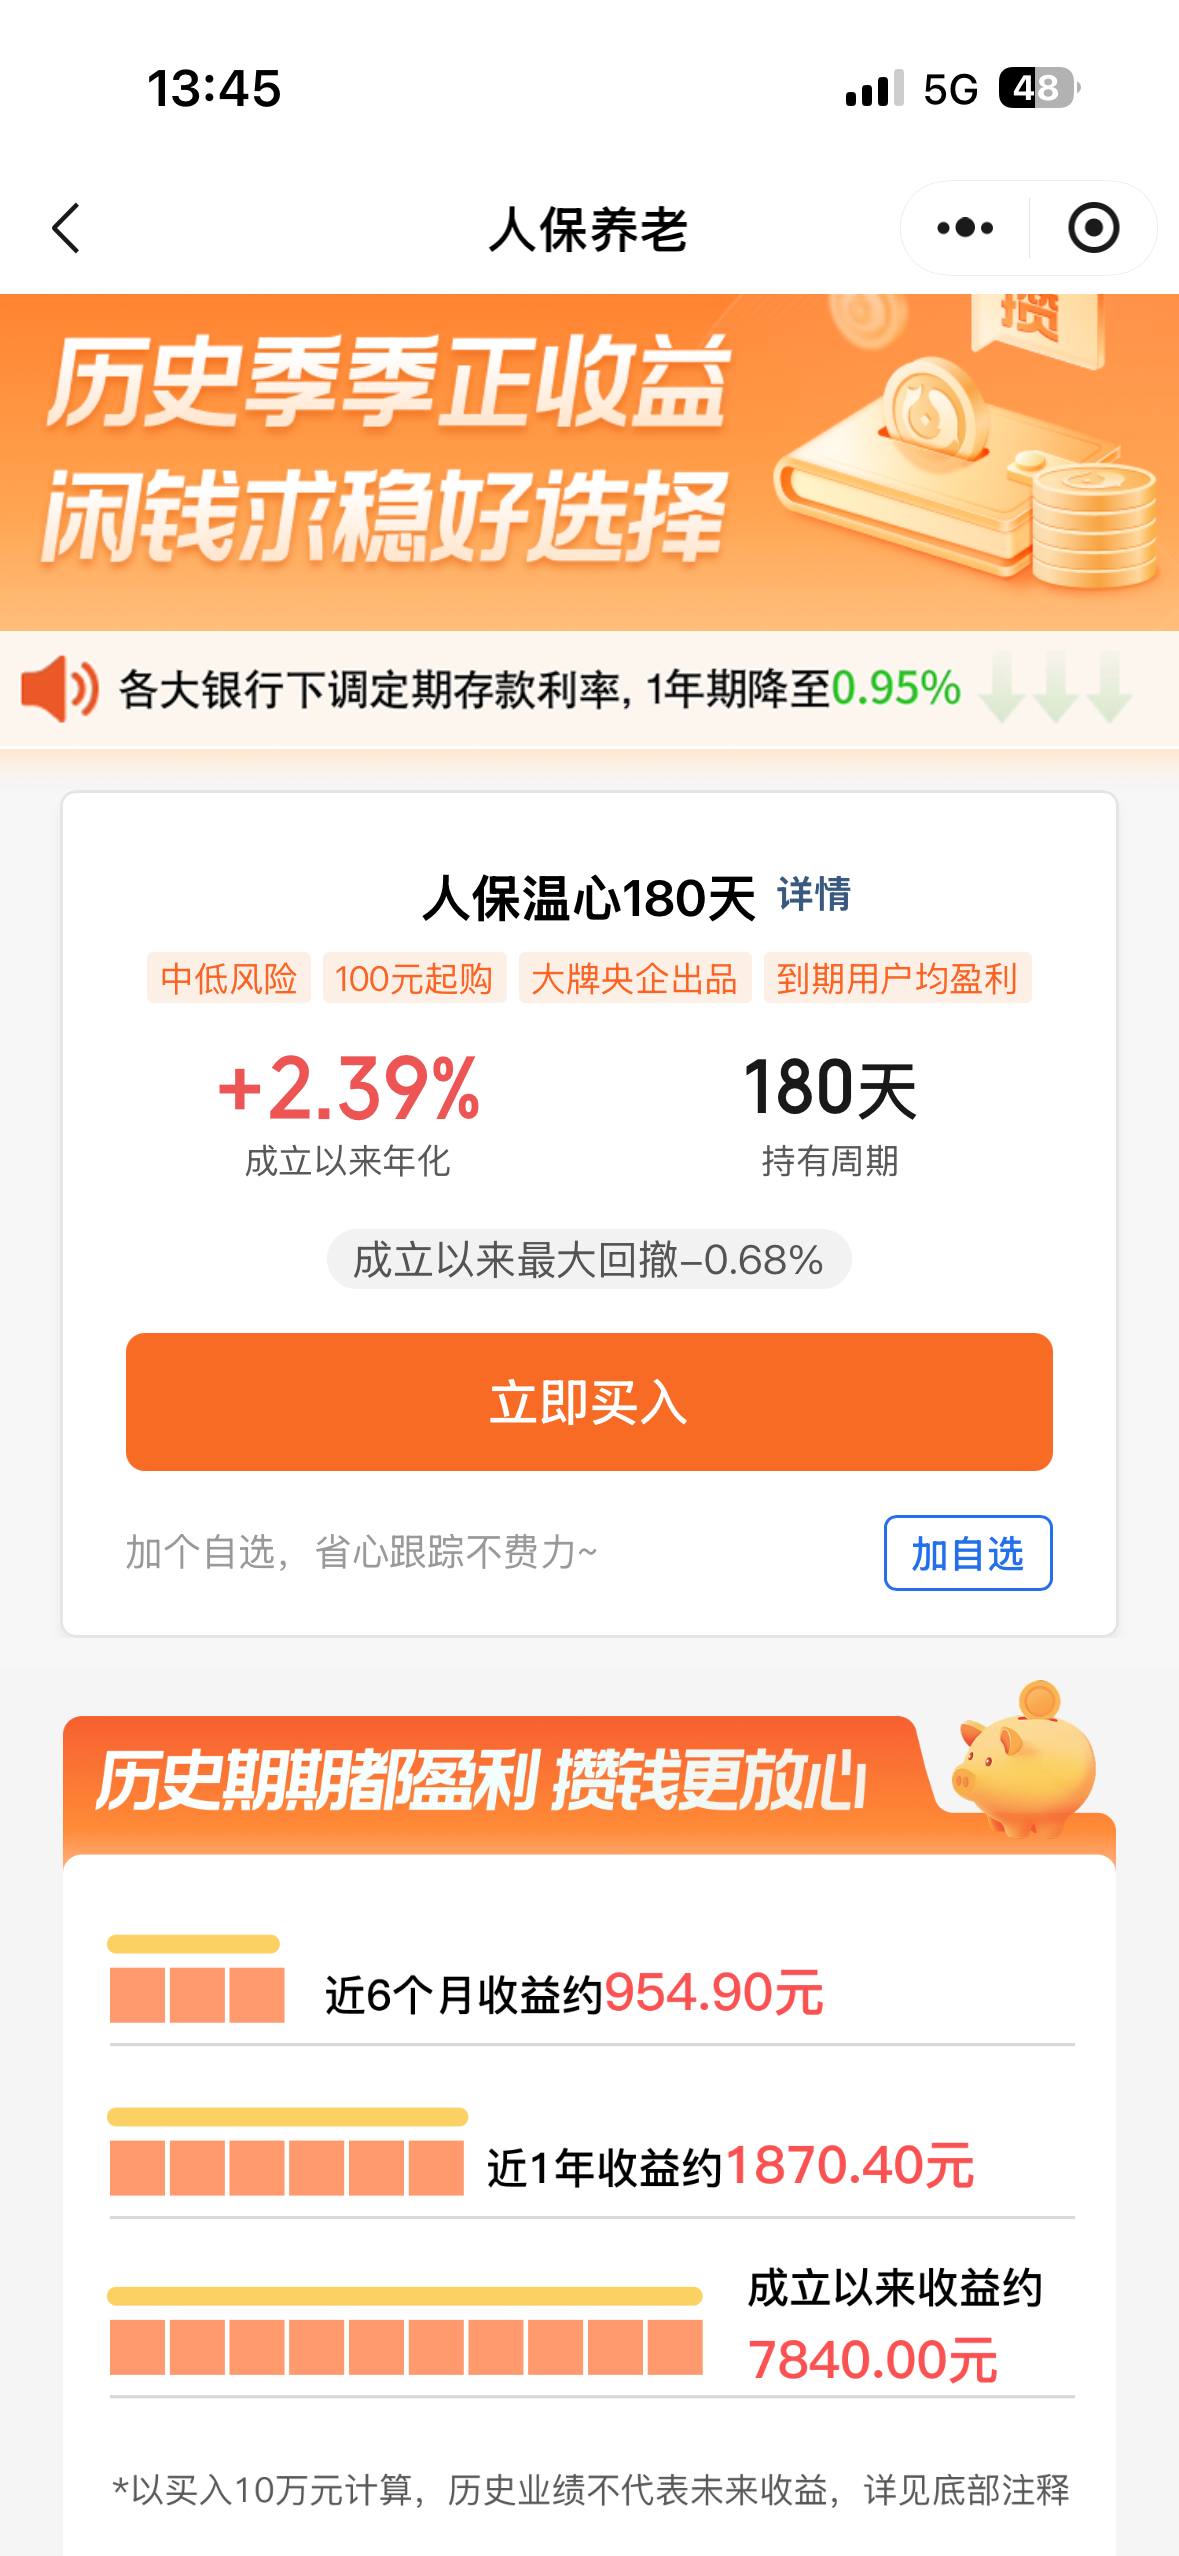
The reporter also found that on the purchase pages of some commercial pension products on the Wealth Management Platform, there is a prompt bar with a broadcast symbol at the top, which reads: "Major banks have lowered their fixed deposit interest rates to 0.95% for 1-year term", and three green downward arrows are drawn.
The details page of a product called "Human Warm Heart 180 Days" has the above prompt. Below the prompt bar is the red number with an annualized rate of "+2.39%" since the establishment of this product.
The reporter found through inquiry that the product is called PICC Elderly Care Warm Heart Years No. 3 Fixed Income Commercial Pension Product, and the following content is bolded in its risk warning letter:Our company does not guarantee a certain profit, nor does it guarantee the principal and minimum return. Please fully understand the product risks and make cautious decisions. The income or loss generated from the asset management and operation of this commercial pension product shall be borne by the policyholder. Please choose a commercial pension product based on your own needs and risk tolerance。
Article 10 of the Measures also establishes a red line for online marketing content, with Article 4 explicitly stating that insurance liability or insurance product benefits shall not be exaggerated, and insurance product benefits shall not be simply compared to financial products such as deposits and asset management products. At the same time, the "Measures" have put forward clear requirements for promotional language: no suggestive language such as "low risk", "low threshold", "instant payment", "high return", "low interest rate", "no cost" shall be used.
An insurance industry insider stated that some pension insurance companies do have a state-owned background, but the credit rating of shareholders cannot be equated with the risk of financial products. Changes in shareholder background cannot change the fluctuation of product net value and the self bearing nature of profit and loss. Labeling insurance products as "savings" can easily lead to misleading information.

Haosi Power CPO Hu Shichuan: Follow us to go global and promote our products worldwide
Lotus Group CEO Feng Qingfeng: The goal is not to catch up with Ferrari, but to surpass Ferrari
Haosi Power Global CTO/Aurora Bay Global CEO Zhao Fucheng: The world's largest independent powertrain supplier is ready


 Subscribe