Economic Observer Follow
2026-10-23 12:35

Economic Observer reporter Lao Yingying
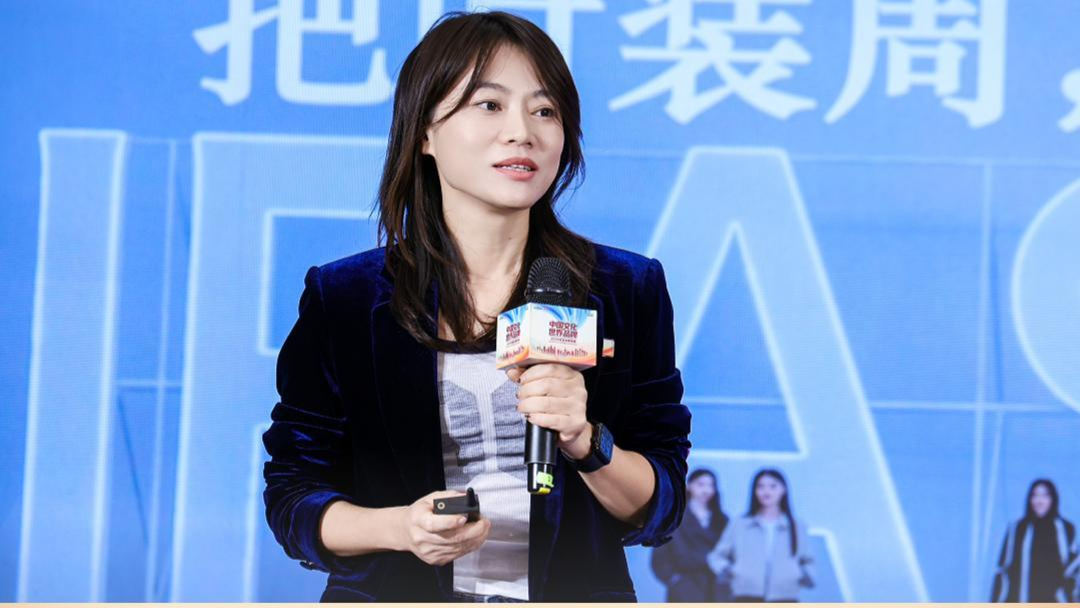
AI (artificial intelligence) has become a key variable affecting the macro-economy, and the discussion about whether there is a foam in AI continues to heat up. On October 22, at the 2026 Fortune China 500 Forum, Hu Weijun, Chief Economist of Macquarie Group in China, Li Xunlei, Chief Economist of Zhongtai Financial International Co., Ltd., Zhang Yu, Chief Economist of Huachuang Securities, Liu Xiaoshu, Chief Economist of Bank of Qingdao, and other topics were discussed around AI industry cash flow, foam risk, industrial chain profit distribution and other issues. The experts at the meeting agreed that corporate cash flow is the core indicator to judge the AI foam dispute, and the cash flow of upstream, midstream and downstream enterprises in the current AI industry chain is significantly differentiated.
Liu Xiaoshu conducts analysis and judgment from the segmented links of the industrial chain. He stated that in the upstream of the AI industry, in terms of computing power and optical modules, both operating cash flow and free cash flow are positive; In the midstream stage, the operating cash flow of large model manufacturers is generally positive, but due to the lack of a universally applicable business model, their free cash flow remains negative; In the downstream stage, there is a clear differentiation in the application end. Some applications have found high-quality scenarios, and their operating cash flow continues to grow, but the sustainability of cash flow needs to be verified. There are also many application projects that lean towards conceptual speculation, and their operating cash flow and free cash flow performance are not ideal.
Li Xunlei also stated that the overall cash flow of the AI industry has not yet reached the point of "collapse", but the internal structure of the industry is different. At present, 70% of the income of AI industry is concentrated in the upstream, which is different from the Internet industry in the same year. The later profits of the Internet industry are mainly concentrated in the downstream. Nowadays, the AI industry is profitable for the upstream production end, but not for the downstream application end. If the downstream continues to struggle to make profits, the upstream may also be affected in the future. At present, the industry is still in the stage of capital expenditure expansion, and capital expenditure will continue to increase in 2027, but the growth rate will significantly slow down. There is still a certain degree of uncertainty in how profits will be distributed between the upstream, midstream, and downstream of the AI industry chain. The key next step is to see if profits can be smoothly transmitted downstream.
In Zhang Yu's view, the biggest difference between this round of AI market and the Internet foam of that year is that this round of AI market is mixed with complex sovereign competition factors, and the United States is no longer a complete monopoly in terms of industrial and financial pricing. From this, we can deduce several judgments: First, the world is no longer a unified market, but a segmented market, which is different from the Internet era. Many domestic models and applications may not be able to enter the US market, and vice versa. Second, in the context of market segmentation, theoretically, the peak of AI's valuation in this round will be lower than that of the Internet foam. At that time, there were no sovereign factors interfering, and theoretically, the total demand scale that could be reached globally by any single global leading enterprise was significantly higher than this round.Thirdly, companies at the same position in the AI industry chain, whether in terms of computing power supply, tool services, or application implementation, will have different valuations and trends depending on their country of origin. Fourthly, the current AI market is not fluctuating synchronously. When the technology Internet stock fell, the Asian and European markets followed, but this round of AI market was disturbed by sovereign factors, and the segmented market would suffer from periodic dislocation.
Hu Weijun believes that AI is an emerging industry and it is difficult to have strong and stable cash flow like mature industries, so it is understandable that some companies have weak cash flow. But for the emerging technology track, financing costs and industry narratives are particularly critical, and currently both are facing unfavorable situations. On the one hand, the rising interest rate of treasury bond has pushed up the financing cost of the global market; On the other hand, the revenue growth rate of top AI companies has significantly slowed down, and the market is beginning to worry that fierce competition will suppress the long-term profitability of AI companies.
He also stated that in order to determine the long-term sustainability of the AI industry, three key factors need to be observed: first, whether financing costs will continue to rise; Secondly, whether the industry competition pattern can be improved and whether the profit growth rate can be raised again; The third is whether new business models can be developed. At present, the market can focus on the new landing applications of AI in fields such as technology and health. If feasible business models can continue to emerge, the current trend of AI industry prosperity is expected to continue.


 Subscribe