2026-10-15 16:05

Economic Observation Network Citigroup released a research report on October 14th, analyzing the recent stock price performance, third quarter performance, and related business progress of Weichai Power (02338. HK).
Institutional Perspective
Citigroup pointed out that Weichai Power's stock price has fallen by 10% in the past week, and the valuation gap with the AIDC index has widened to the widest point of the year - H-shares are about 39% lower than the relevant weighted index
The above content is based on publicly available information and does not constitute investment advice.
ST Qingyue fined 172 million yuan for suspected fraudulent issuance and illegal letter disclosure
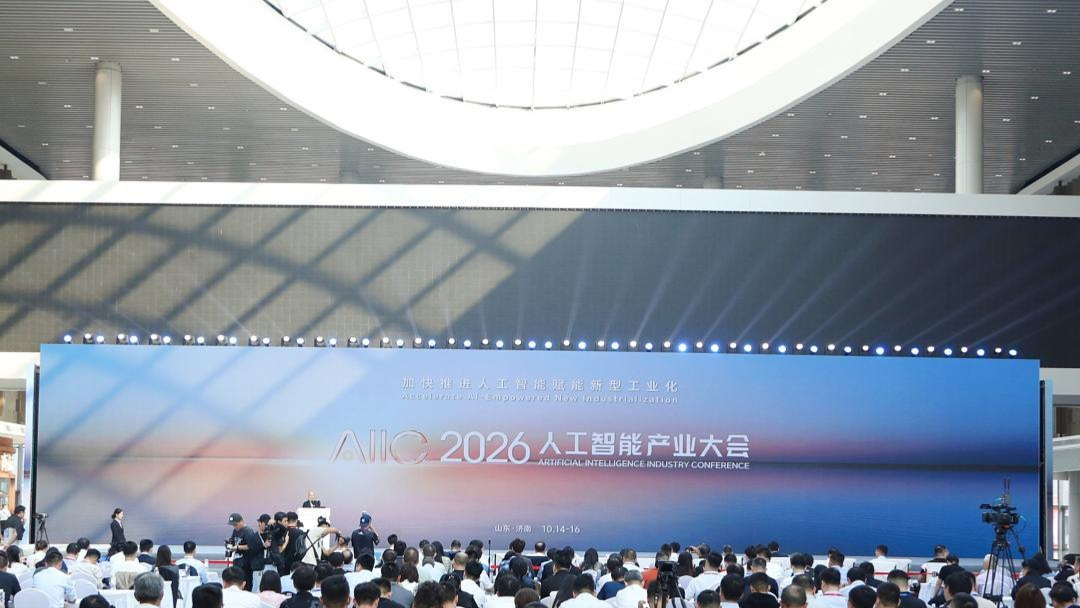
Focusing on "Artificial Intelligence Empowering New Industrialization", the 2026 Artificial Intelligence Industry Conference opens in Jinan
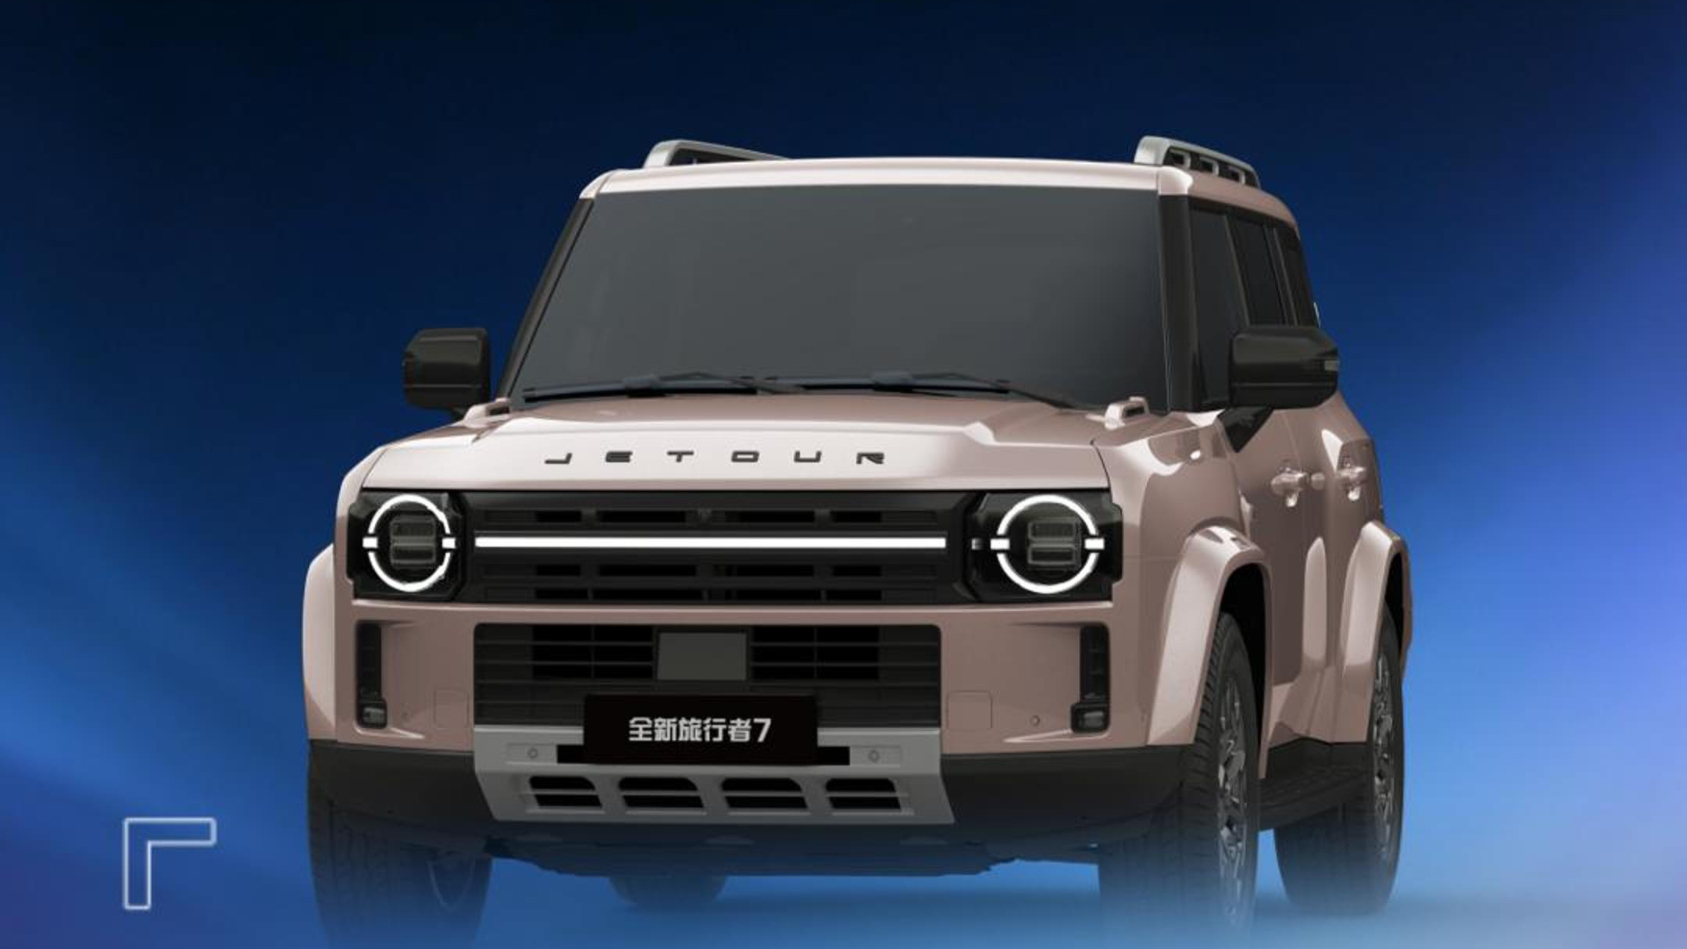
Can Traveler 7 take care of both commuting on weekdays and mountain trips on weekends? This time, the all-new Jetour Traveler 7 will focus on its "Keyo" # Smart Beauty Travel Champion Box # Kecheng Keyo Keyo Travel # 7 Series Square Box New Benchmark # New Traveler 7 Renewal Surprise Price Starting from 125900 yuan