Economic Observer Follow
2026-10-14 18:48

Recently, Tang Wei has discussed with the Planning and Finance Department multiple times whether to raise the interest rate for the 3-year large denomination certificate of deposit to be issued in the fourth quarter from 1.8% to 2%.
As the head of deposit business at a rural commercial bank in East China, Tang Wei was previously busy lowering deposit interest rates and maintaining the situation of net interest margin bottoming out and recovering.
If we don't follow up and raise the issuance interest rate of 3-year large denomination certificates of deposit, customer deposits will face pressure to be lost again, "Tang Wei told reporters.
Tang Wei said that raising the issuance interest rate of large denomination certificates of deposit will inevitably drag down the net interest margin, but at present, more attention should be paid to the risk of deposit loss. Affected by factors such as the issuance of large denomination certificates of deposit by large banks in August, his rural commercial bank has suffered retail deposit losses of over 100 million yuan in the past month. If the interest rate on large denomination certificates of deposit is not raised again, the bank's retail deposit loss in the fourth quarter is expected to exceed 300 million yuan.
Lou Feipeng, a researcher at China Postal Savings Bank, believes that one important factor in the current gradual increase in interest rates for large denomination certificates of deposit by small and medium-sized banks is to alleviate the pressure of deposit loss caused by large banks launching 5-year certificates of deposit.
In Tang Wei's view, there is another underlying reason why small and medium-sized banks have raised the interest rates for issuing large denomination certificates of deposit. Small and medium-sized banks have encountered obstacles in expanding their enterprise payroll and fund settlement businesses, resulting in slow progress in optimizing deposit structures and increasing the proportion of low interest current deposits. Therefore, they have chosen to issue high interest deposit products to stabilize their debt side funds.
Raise Interest Rates
After multiple large banks issued large denomination certificates of deposit in August, Tang Wei's rural commercial bank decided to quickly follow suit.
Initially, Tang Wei and the Planning and Finance Department proposed to issue a 3-year large denomination certificate of deposit product with a minimum deposit of 200000 yuan, an annualized interest rate of 1.8%, and a fundraising amount of 300 million yuan.
Given that the maximum annualized interest rate for 5-year large denomination certificates of deposit launched by large banks is 1.6%, we expect an annualized interest rate of 1.8% to be sufficient to attract customers to choose to renew their deposits, "said Tang Wei.
Recently, Xishang Bank and Yongfeng Bank have respectively launched 3-year personal large denomination deposit certificates with a minimum deposit of 200000 yuan and an annualized interest rate of 1.9% -2%.
Tang Wei felt a little restless when he saw this news. On October 8th, the senior management of Tang Wei's rural commercial bank convened a meeting with the deposit department, planning and finance department, and risk control department to discuss whether to raise the interest rate for issuing large denomination certificates of deposit to 2%.
The senior executive of the rural commercial bank stated that during the holiday period, several high net worth individual clients proactively asked him if they plan to launch large denomination deposit certificates with an annualized interest rate of 2% in the near future. If not, they intend to "switch" their maturing deposits and seek higher deposit interest income.
At the meeting, the Planning and Finance Department initially voted against it, citing that the bank had continuously lowered the fixed deposit interest rate by more than 70 basis points in the second and third quarters, causing the net interest margin to bottom out and rebound by 4 basis points. If the interest rate for issuing large denomination certificates of deposit is raised in the fourth quarter, it will inevitably increase the pressure on the debt side to pay interest, or lead to the net interest margin returning to a downward trend.
Tang Wei's attitude is that, compared to the pressure of net interest margin, the more urgent business challenge at present is to curb deposit loss and stabilize debt side funds.
Faced with differing opinions between the planning and finance department and the deposit department, the senior management of Agricultural and Commercial Bank of China did not make a final decision.
On the morning of October 12th, the senior management of the Rural Commercial Bank approached Tang Wei and proposed a "win-win" plan - raising the interest rate for large denomination certificates of deposit to 2% while reducing the fundraising scale by one-third to 200 million yuan. This can not only stabilize the debt side funds by raising the interest rate of large denomination certificates of deposit, but also alleviate the interest payment pressure on banks and maintain the trend of net interest margin recovery.
Tang Wei stated that this compromise plan has been approved by the Planning and Finance Department and is currently being filed with the local financial regulatory authorities.
Li Bo works as the head of retail business at a city commercial bank in central China.
He said that the increase in interest rates for large denomination certificates of deposit or fixed deposits by small and medium-sized banks has also had an impact on their bank's retail deposit collection.
Over the past week, several branch managers have provided feedback to Li Bo that some high net worth individual customers have either switched to large banks' large denomination certificates of deposit or actively searched for small and medium-sized bank large denomination certificate products with interest rates around 2%, resulting in a 6 percentage point decrease in the renewal rate of retail deposits in the branch compared to August and September, to around 70%.
Recently, Li Bo's city commercial bank has also accelerated the issuance of large denomination certificates of deposit, planning to raise the issuance interest rate from 1.8% to 1.95%.
A 'interlude'
Tang Wei said that the financial department's relaxation in raising the interest rate for issuing large denomination certificates of deposit is conditional.
On the morning of October 13th, the head of the planning and finance department approached him and calculated an account: since the beginning of this year, the weighted average loan interest rate of this rural commercial bank has fallen to 3.8%. If the bank continues to issue large deposit certificates at an annualized interest rate of 2% to attract deposits, after deducting expenses such as operation, risk control, and overdue bad debt write off, the bank's net interest margin will drop to around 1.36%, which is not only lower than the average net interest margin of commercial banks, but will also continue to weaken the bank's profitability.
Therefore, the plan and finance department's proposal to raise the issuance interest rate of large denomination certificates of deposit can only be a "phased measure" and cannot become a "long-term means".
Tang Wei stated that this is a temporary measure to cope with the current pressure of deposit loss, and he also does not want to see banks relying on high interest deposit products to stabilize their debt side funds for a long time.
Professor Miao Jinchun from the School of Business at Soochow University believes that the core deposit foundation of small and medium-sized banks is relatively weak, and they may have to issue high interest deposit products to attract deposits at certain stages. However, given the pressure of stabilizing and recovering net interest margins and regulatory constraints on the debt side costs of banks, it is difficult for small and medium-sized banks to issue high interest deposit products for a long time.
After the National Day holiday, the senior management of Li Bo's city commercial bank convened a meeting with multiple business department heads to discuss whether to follow up on raising interest rates. The senior management emphasized that in the environment of continuous decline in loan interest rates, the key for banks to maintain high profitability and net interest margin lies in continuously optimizing deposit structure and reducing debt financing costs. The increase in the issuance interest rate of large denomination certificates of deposit this time is a "interlude" in preventing deposit loss at the current stage.
Li Bo told reporters that at the meeting, bank executives also emphasized that they must not continue to rely on issuing high interest deposit products to "attract deposits", and that deepening customer refined services and expanding and strengthening settlement businesses such as project payment and salary payment are the "fundamental solutions" to continuously stabilize debt side funds and increase the proportion of low interest active deposits.
Tang Wei admitted that the senior management of his rural commercial bank also knows well that the key to stabilizing and recovering the bank's net interest margin at present lies in actively expanding business such as enterprise salary payment and fund settlement, in order to increase the proportion of low interest current deposits and further reduce financing costs on the debt side.
Comprehensive Customer Expansion
At the beginning of this year, the senior management of Tang Wei's rural commercial bank requested the corporate business team to fully expand the company's payroll agency, supply chain fund settlement, engineering payment agency and other businesses, striving to increase the proportion of current deposits from 22% at the end of last year to 32%.
To achieve this work goal, Tang Wei admitted that the difficulty is not small.
In the first three quarters of this year, Tang Wei accompanied bank executives to visit local leaders of large and medium-sized enterprises multiple times, promoting products such as salary payment agency, supply chain fund settlement, and engineering payment agency. But he found that these business leaders are more willing to hand over these businesses to large banks.
Large banks are stronger than the vast majority of small and medium-sized banks in terms of branch layout, response speed, comprehensive financial service capabilities, and customized product service design, so business leaders naturally feel a sense of belonging, "Tang Wei said frankly. The person in charge of corporate business at the branch network also expressed their feelings at the internal business exchange meeting, stating that local large banks have "packaged" corporate credit, salary payment, fund settlement, enterprise cash management and other businesses, providing a package of financial service solutions to local large and medium-sized enterprises, making it more difficult for small and medium-sized banks to "seize opportunities".
As of the end of the third quarter of this year, the proportion of current deposits in Tang Wei's rural commercial bank has only reached the 27% mark, which is still a certain gap from the target value of 32%.
Recently, Tang Wei's Rural Commercial Bank conducted a business review to identify its own shortcomings.
Through retrospective analysis, we have identified two issues in our work: firstly, excessive focus on local large and medium-sized enterprises, neglecting the fund settlement needs of local small and micro merchants; secondly, in the process of dealing with enterprises, we blindly focus on communicating with enterprise leaders, lacking a good trust relationship with enterprise financial accounting personnel to solve the latter's fund payment and receipt needs in actual work processes, "Tang Wei told reporters. In fact, financial accountants in enterprises also have a great say in choosing which bank to use for salary payment, supply chain fund settlement, and engineering payment products.
Tang Wei stated that the bank quickly adjusted its corporate business strategy for the fourth quarter, requiring branch and branch corporate customer managers to visit 10 local corporate financial accounting personnel and small and micro merchants every week, and provide feedback on the specific fund payment and receipt needs of the visiting enterprises in areas such as salary payment and supply chain fund settlement on Friday. The bank's product department will collaborate to provide corresponding financial product services.
The bank also plans to focus on assessing the service satisfaction of corporate customers and provide special rewards to corporate customer managers who rank high in customer satisfaction, "said Tang Wei.
Li Bo told reporters that since the beginning of this year, his city commercial bank has been continuously promoting business collaboration and expanding customer base.
The so-called business collaboration and customer expansion mainly refers to the visit of personnel from different business departments of banks to enterprises, comprehensively understand the differentiated financial service needs of enterprises and employees, and provide comprehensive financial services. For example, customer managers from both corporate and retail business departments visit the company together. After the corporate business customer manager recommends salary payment products, the retail business customer manager introduces multiple salary wealth management products, thus opening up the entire financial service loop from salary payment to employee wealth management, and retaining more salary type current deposits for the bank.
Li Bo told reporters that the senior management of the bank has repeatedly inquired about the specific effectiveness of business collaboration in expanding customer base and expanding the industry. At the same time, they emphasized that the era of "interest rate competition" in attracting deposits is over, and in the future, competition among banks in attracting deposits will compete for customers' refined service capabilities.
(At the request of the interviewee, Li Bo is using a pseudonym)

ST Qingyue fined 172 million yuan for suspected fraudulent issuance and illegal letter disclosure
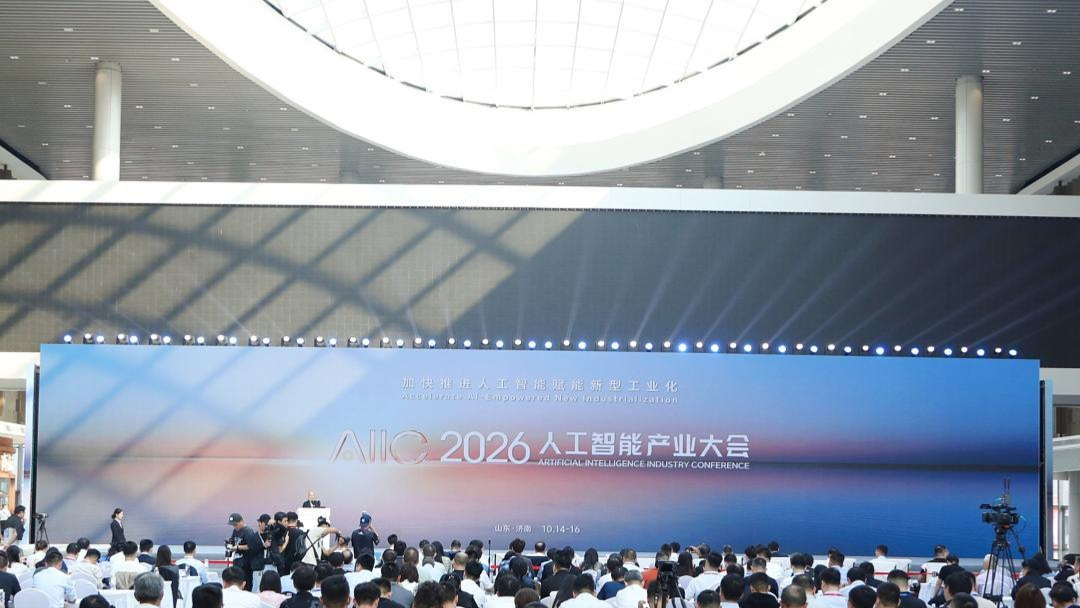
Focusing on "Artificial Intelligence Empowering New Industrialization", the 2026 Artificial Intelligence Industry Conference opens in Jinan
Can Traveler 7 take care of both commuting on weekdays and mountain trips on weekends? This time, the all-new Jetour Traveler 7 will focus on its "Keyo" # Smart Beauty Travel Champion Box # Kecheng Keyo Keyo Travel # 7 Series Square Box New Benchmark # New Traveler 7 Renewal Surprise Price Starting from 125900 yuan


 Subscribe