2026-10-09 11:46

Recently, the State Administration of Financial Supervision and Administration of China issued a notice on the compulsory insurance business for motor vehicle traffic accidents in 2025. Data shows that in 2025, the premium income of compulsory insurance will be 285.2 billion yuan, and the compensation expenditure will be 252.4 billion yuan; After underwriting a loss of 29.6 billion yuan and sharing 6.6 billion yuan of investment income, the operating loss still reached 23 billion yuan.
1、 The institutional reasons behind the 23 billion loss
The full name of compulsory insurance for motor vehicle traffic accidents is "Compulsory Insurance for Motor Vehicle Traffic Accident Liability", which is the first statutory compulsory insurance in China and has been implemented for 20 years since 2006. Its biggest features are two: one is mandatory, as long as you are on the road, you have to buy it; The second is not for profit, and the compensation is for the third party who suffered in the traffic accident.
Bai Yuwei, Chief Expert on Beidou Digital Car Insurance and Insurance Industry Application of the National Development and Reform Commission, stated that the periodic losses of compulsory traffic insurance are determined by its institutional nature.
In terms of revenue and compensation in 2025, compensation expenses increased by 11.6% year-on-year, while premium income only increased by 5.2%, forming a significant "scissors gap" between the two; From the perspective of price mechanism, the average car premium is 762.1 yuan, a slight decrease of 0.1% year-on-year, and the pressure of compensation is increasing, but the premium has not been adjusted accordingly; From an operational perspective, management and service costs reached 53.8 billion yuan (including 1.07 billion yuan from the rescue fund), a year-on-year increase of 2.8%. The combination of these three aspects creates a situation of "paying more, receiving less, and managing more expensive".
Simply put, compulsory insurance is a public welfare guarantee, but it operates according to the rules of commercial insurance, so losses may be obvious. However, since it is a national statutory and inclusive livelihood security system, we cannot simply look at the book losses.
Long Ge, Deputy Director of the Innovation and Risk Management Research Center at the University of International Business and Economics, said, "From the perspective of the rate fluctuation mechanism, car owners who drive safely and have not been responsible for accidents for many years enjoy a premium reduction discount, while the premium increase for insured vehicles is limited (the fluctuation range of compulsory traffic insurance itself is relatively narrow). In addition, the background factors such as the annual increase in personal injury compensation standards and the continuous growth of motor vehicle ownership have led to an expansion of the number of insured cases. The faster growth rate of compensation than premium growth is actually structural and trend oriented. This precisely indicates that compulsory traffic insurance has compensated the money that should have been compensated, trapped the bottom of the bag, and spent the money on the blade." From this perspective, the 23 billion yuan loss should not be simply attributed to poor management, but should be more appropriately released. Examine within the institutional framework.
2、 The cost of compensation is getting higher and higher
The continuous increase in compensation costs for compulsory traffic insurance in 2025 is a common challenge faced by the industry and the result of multiple objective factors. This is mainly reflected in five aspects:
Firstly, the intensity of motor vehicle usage continues to rise. The annual turnover of highway personnel reached 61.226 billion, a year-on-year increase of 3.3%, and the number of compulsory traffic insurance cases reached 51.359 million, a year-on-year increase of 7.3%. The increase in case volume constitutes the fundamental support for the increase in compensation.
Secondly, the standards for personal injury protection have been substantially improved. The insurance industry implements the requirements of unified standards for personal injury compensation for urban and rural residents, and calculates disability compensation, death compensation, etc. uniformly using the standards for urban residents. By 2025, the per capita disposable income of residents in China will be 43377 yuan, with a nominal growth of 5.0%, promoting the increase of compensation standards for death and disability.
Thirdly, there is a structural increase in medical expenses. The diagnosis and treatment costs for traffic accident victims are continuously increasing due to multiple factors such as advances in medical technology, prices of drugs and consumables, and an increase in examination items. As the "first line of defense" for the treatment of accident victims, compulsory traffic insurance passively undertakes the transmission of all costs.
Fourthly, the proportion of new energy vehicles is rapidly increasing. In 2025, the industry will underwrite 43.58 million new energy vehicles, accounting for 12.1% of the total insured motor vehicles, up from 8.9% in 2024. According to information released by the Chinese Actuarial Association and other organizations, new energy vehicles exhibit the "two highs" characteristics of high frequency of accidents and high maintenance costs, and the overall operation is in a loss making range.
Fifth, the optimization of claims services brings about an "explicit" effect. The measures of hospital green channel, full advance payment, and police insurance linkage for fast processing and compensation continue to be promoted. Cases that were previously unable to be reported or compensated in a timely manner due to cumbersome processes have entered the normal compensation channel, and the compensation data is more authentic and complete.
These five factors are not short-term fluctuations, but long-term trends. The direction of these variables is almost one-way, including the increase in residents' income, the improvement of personal injury protection standards, the rise in medical expenses, the increase in the penetration rate of new energy vehicles, and the continuous optimization of claims services. This means that the compulsory traffic insurance is not facing cyclical losses that can be easily overcome, but rather an institutional test of whether the actuarial model, rate mechanism, and risk sharing system can match the changes in social structure. If the institutional design cannot keep up with these changes, losses will be the norm.
3、 Industry complains of losses, car owners complain of high prices
Although the compulsory traffic insurance has incurred a loss of 29.6 billion yuan, in recent years, some car owners still feel that car insurance is becoming increasingly expensive. This may seem contradictory, but it actually stems from two types of misalignment.
One reason is that the decrease in average premiums masks group differentiation.
In 2025, the average premium for compulsory insurance vehicles will be 762.1 yuan, a slight decrease of 0.1% year-on-year. However, under the rate fluctuation mechanism, car owners who have not had any accidents for many years will enjoy a downward discount, while high-risk car owners will have their premiums increased. However, the floating range of compulsory traffic insurance is limited, and the increase in compensation costs has not been fully transmitted to high-risk groups, resulting in an increase in industry losses.
The second is the implicit transmission of loss pressure through commercial auto insurance.
On the one hand, the adjustment of the basic premium rate of compulsory traffic insurance must follow strict procedures, and it is difficult to directly increase the price in the short term. Some insurance companies use commercial auto insurance quotes, underwriting, and bundling to alleviate pressure. Some car owners have reported that they have not had any accidents for three consecutive years, but their prices have increased; I only want to purchase compulsory traffic insurance and third-party liability insurance, but I am required to add seat insurance and driver liability insurance, otherwise I will not be able to issue the policy normally. After the complaint, the commercial insurance premium was actually raised. This kind of bundling and implicit price increase transforms the loss of compulsory traffic insurance into the perception of car owners that 'car insurance has become more expensive'.
On the other hand, the total liability limit of compulsory traffic insurance is 200000 yuan, including 180000 yuan for death and disability, 18000 yuan for medical expenses, and only 2000 yuan for property losses. Damaging luxury cars or causing serious injuries, exceeding the limit must be borne by the owner. The vast majority of car owners must purchase commercial third-party insurance and vehicle damage insurance. When commercial insurance prices increase due to the pressure of digesting losses in the industry, car owners feel that the overall car insurance has become more expensive, rather than a separate price increase for compulsory insurance.
Long Ge pointed out that compulsory traffic insurance is essentially a "statutory bottom line insurance", and commercial car insurance is still needed for large payouts. The industry will use commercial car insurance quotes, underwriting, and bundling to digest pressure. "The real perception of car owners is that 'compulsory traffic insurance is losing money on paper, while commercial car insurance is implicitly expensive'
4、 To turn losses around, we cannot just ask car owners to pay more
Reversing losses cannot rely solely on a single approach, but requires the construction of a four-dimensional system of "adjusting rates, reducing costs, strengthening collaboration, and optimizing governance". The most direct path is a gradual rate adjustment: based on a rough estimate of a 23 billion yuan gap, an average increase of about 60 yuan in insurance premiums per vehicle can cover it. However, considering social acceptance, regulators are more likely to adopt a refined floating plan based on different vehicle types, uses, and driving behaviors, which not only avoids the "one size fits all" price increase causing public opinion backlash, but also reflects the fairness of risk pricing. In fact, the current floating range of compulsory traffic insurance rates (reduced to -50%) has reserved space for differentiated adjustment. The key is how to scientifically calibrate the rates based on actual accident data from high-risk segmented markets such as new energy vehicles and operating vehicles.
In addition, the rigid cost pressure drop space is limited but the potential is considerable. Among the current management and service costs of 53.8 billion yuan, business taxes and surcharges account for approximately 5.55% -6%, and insurance protection funds account for 0.8%, both of which are statutory expenditures; But technology empowerment can help compress operational costs, such as promoting "one click video claims", AI loss assessment, blockchain certification, etc. According to data from the State Administration for Financial Regulation, the comprehensive cost rate of car insurance in the industry has dropped to 95.8% from January to August 2026, a decrease of about 0.87 percentage points from the industry average of 96.67% in 2025. The strategy of "reducing costs and improving quality" is taking effect.
The deeper way out lies in upgrading the governance model. The essence of the loss of compulsory traffic insurance is the imbalance of the tripartite contractual relationship of "government rules, industry cost bearing, and public protection". In the future, it is necessary to strengthen the coordination between fiscal and tax policies, such as researching the exemption or reduction of compulsory insurance business tax, or providing fiscal subsidies for the extraction of rescue funds; At the same time, deepen the "police insurance linkage" mechanism, integrate insurance data into the traffic governance platform, and reduce accident rates from the source through risk profiling, driving behavior analysis, and high-risk road warning. One less accident, one less compensation, this is the most cost-effective and efficient way to turn losses around.
The 20-year history of compulsory traffic insurance proves that its ultimate value is not in the book profit and loss, but in whether a more fair, efficient, and sustainable road safety community can be built behind the 386 million motor vehicles.
(The author of this article is a researcher at the Jingguan Research Institute)
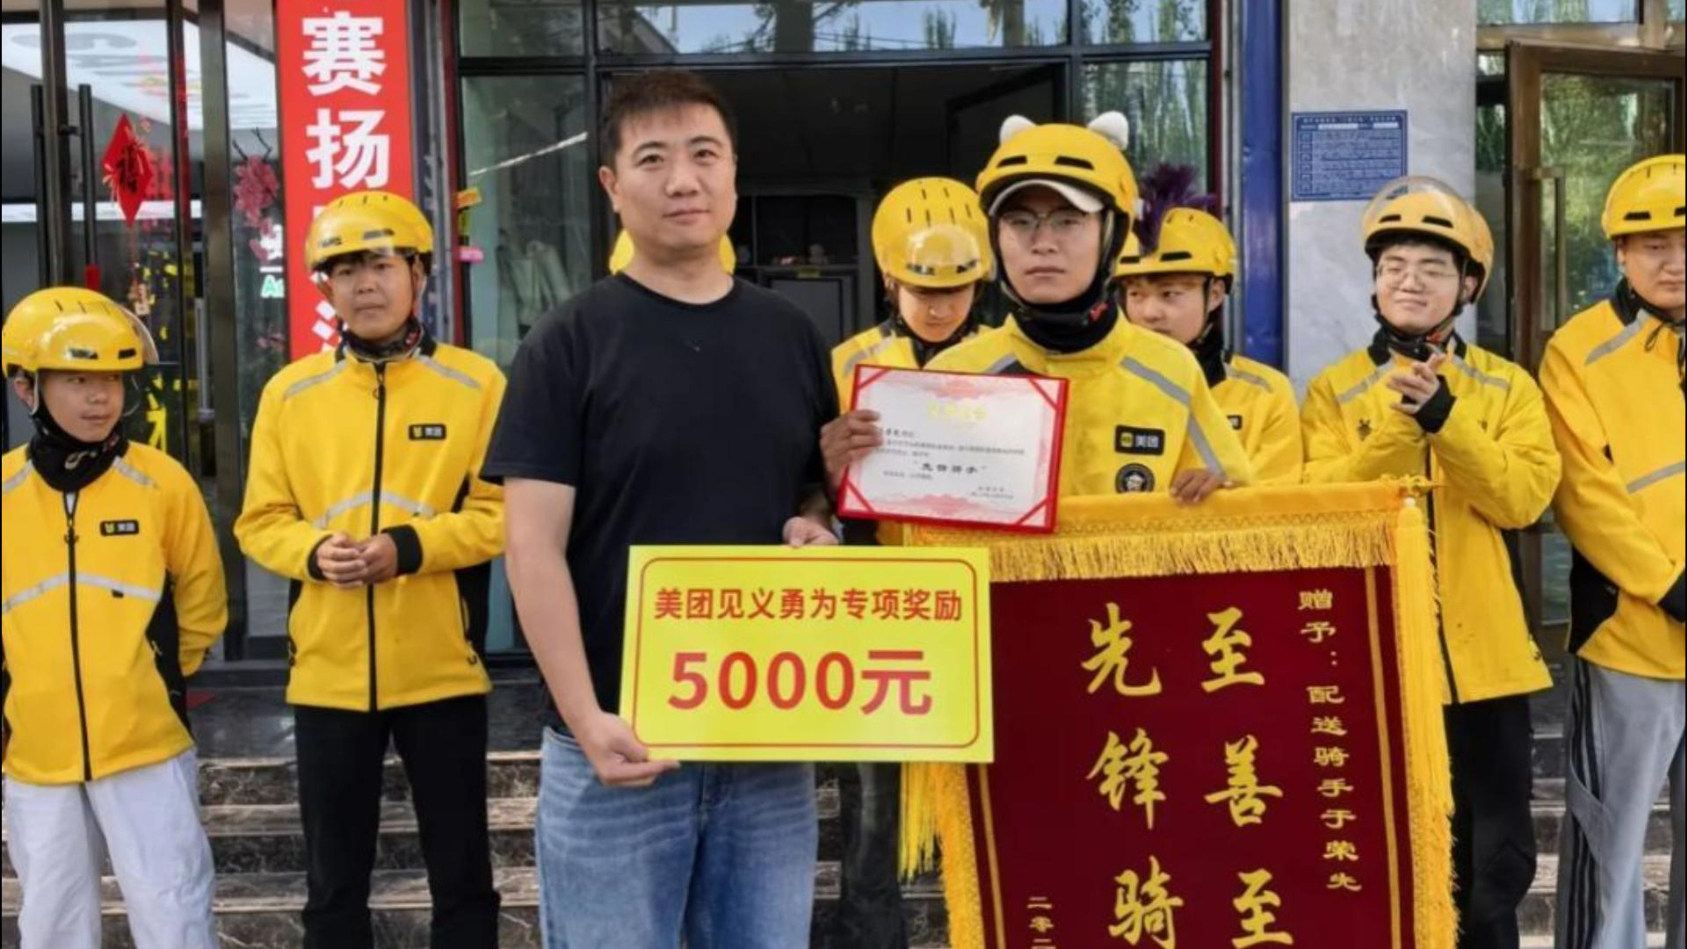
The Central Political and Legal Affairs Commission has released the list of brave warriors for the third quarter of 2026, with Meituan riders Guo Yabin, Yu Rongxian, and Cheng Jianfeng on the list
New "Three Piece Set" in Shopping Mall: Market, IP First Exhibition, First Store
Up to 4.35%! Which bank in mainland China or Hong Kong has a higher fixed deposit interest rate for US dollars?