2026-10-05 17:27

Economic Observation Network Asia Internet Technology (00679) has been classified as a beneficiary target of AI PCB equipment in a securities research report, with revenue growth in mid-2026 but losses attributable to its parent company.
Institutional perspective:
On August 24th, Debon Securities reported that "the demand for AI PCBs has exploded, and technological iterations are driving equipment inflation. It is expected that the growth rate of PCB equipment will exceed 30% in 26-27, and it is recommended to pay attention to industry chain targets such as Asian networking technology." This type of research report is a direct trigger point for the repeated ignition of stock prices. On September 16th and 21st, the stock price rose by more than 5% -10% during this period
Business progress:
The company's main business is electroplating equipment (one of the core equipment in PCB manufacturing), which is therefore classified as a beneficiary target of AI PCB equipment by the market
Performance and business situation:
What needs to be clear is that this is' expected 'rather than' fulfilled '. In mid-2026, the company's revenue was HKD 406 million, a year-on-year increase of about 90%, mainly due to the increase in volume of electroplating equipment business. However, during the same period, the company still incurred a loss of about HKD 19.41 million (dragged down by investment properties), which belongs to the category of "increasing revenue without increasing profits"
The above content is based on publicly available information and does not constitute investment advice.
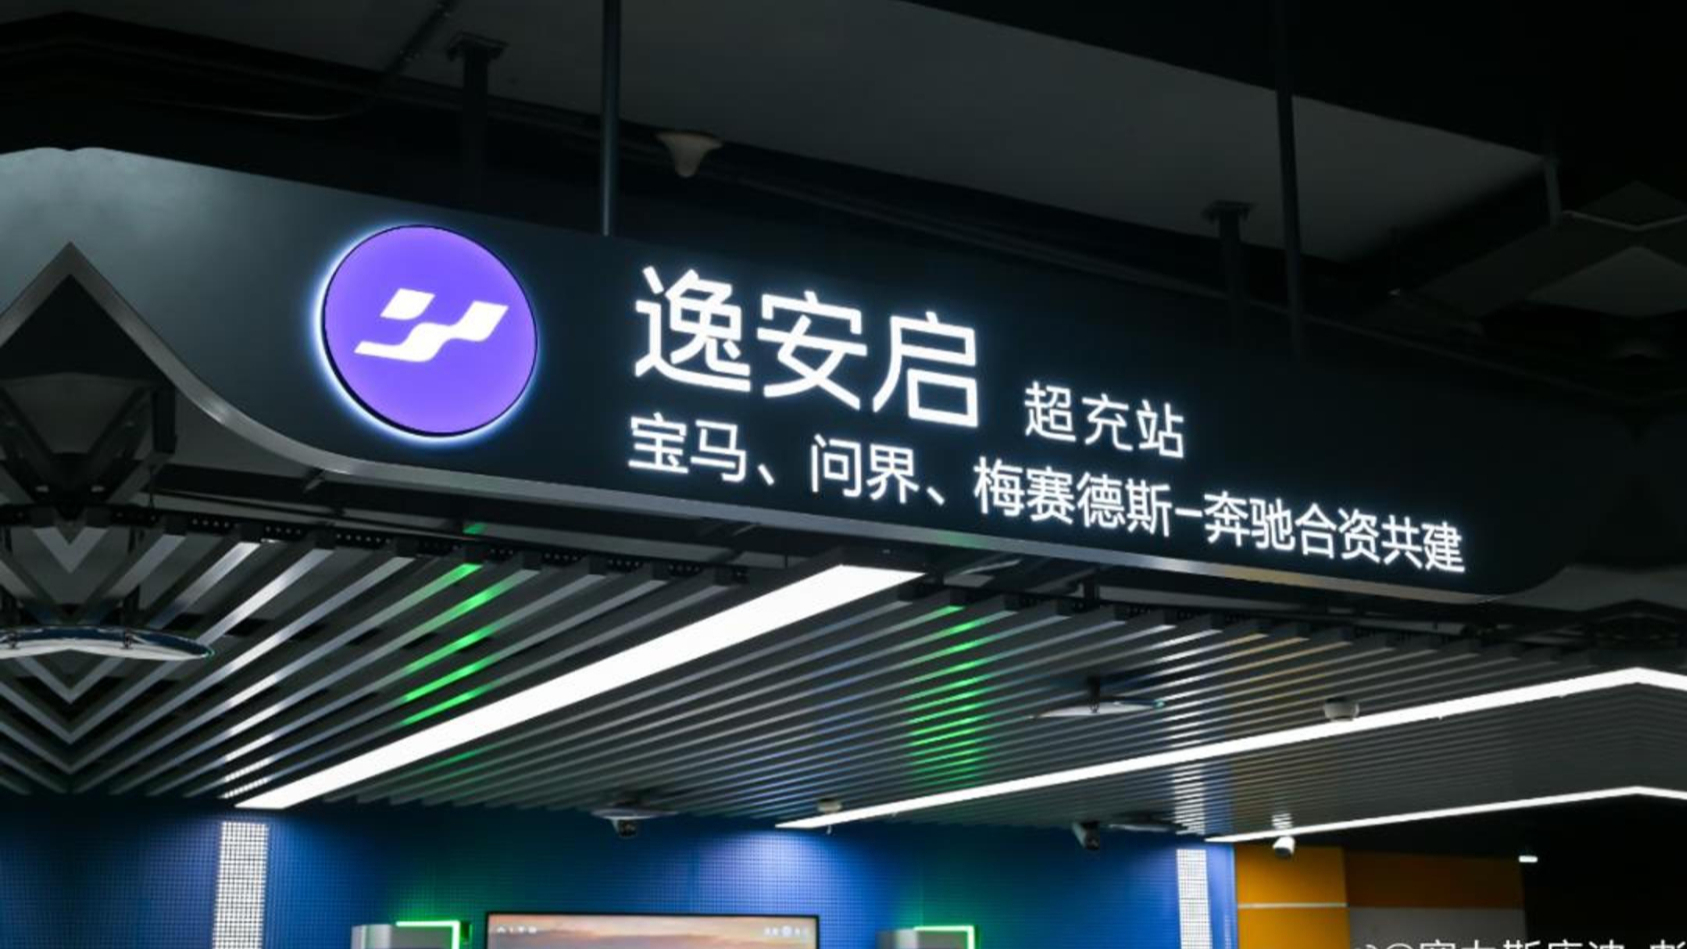
Xilinx officially announced that Wanjie has joined the Mercedes Benz and BMW supercharging camp, with over 600 stations directly connected
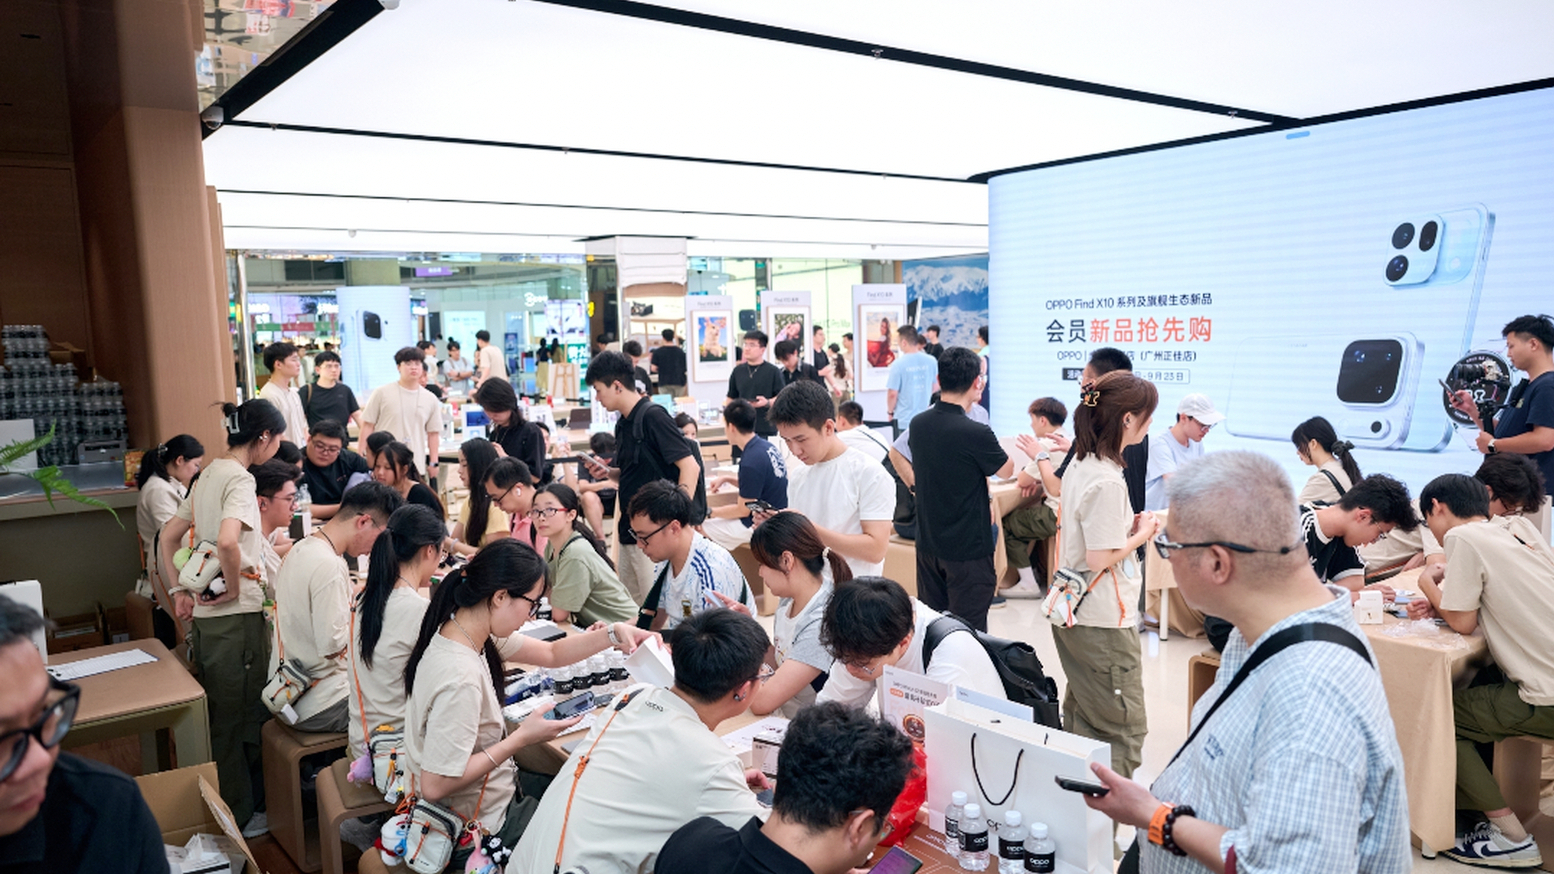
OPPO Find X10 tops sales on the standard version track
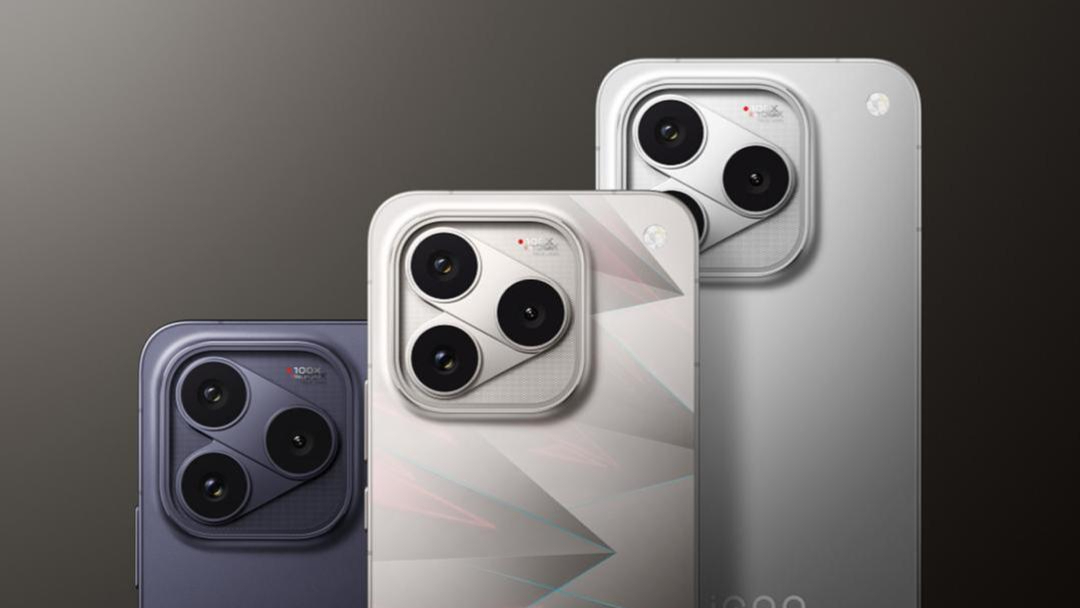
Technology Show | iQOO16 is now available for sale, under the name of Standard Edition, to meet the requirements of Pro Max product strength