2026-10-21 15:01

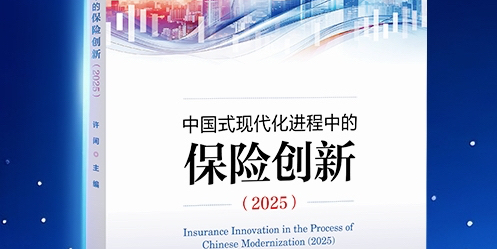
Product Design: Rooting Guarantee in Real Medical Scenarios
Insurance Innovation in the Process of Chinese path to modernization (2025) mentioned that Yuanbao, relying on its technical advantages and deep insight, systematically dismantled the medical habits, consumption ability and risk characteristics of users in the mass inclusive market, and created insurance products closer to the real use scenarios.
In response to users' concerns about "insufficient use of advanced drugs", taking the "Super Medical Insurance · Million Medical Insurance (Premium Edition)" as an example, Yuanbao has set a maximum of 6 million yuan for outpatient cancer special drug protection on top of basic protection, including cutting-edge innovative therapies such as CAR-T and remote medical expenses; The mandatory responsibility covers 174 commonly used anti-cancer special drugs, and the optional responsibility does not limit the list of non imported and purchased drugs, in response to the new demand for hospital purchased drugs after DRG/DIP reform. In response to users' concerns about "not being able to afford", Yuanbao has set up a parallel mode of annual and monthly payments, and uses online insurance and intelligent operation to dilute costs and reduce product rates. In response to users' concerns about "not being able to claim", "Super Medical Insurance · Million Medical Insurance" sets high payout ratios of 60% and 70% for small medical expenses of 10000 yuan or less, which is higher than similar "zero deductible" products in the market. It accurately responds to the public's demand for protection in small medical scenarios and enhances the sense of insurance acquisition.
This design responds to the most common and high-frequency medical scenarios in the inclusive market: what truly consumes household cash flow is often not serious illnesses, but small expenses that cannot reach the deductible amount time and time again. At the same time, it also expands the scope of protection, allowing users to obtain more practical protection. Yuanbao's "Super Medical Insurance · Million Medical Insurance (Premium Edition)" covers multiple medical paths from outpatient and emergency care, hospitalization to purchasing drugs outside the hospital, and postoperative rehabilitation, allowing users to "buy, afford, and be satisfied with compensation". For the industry, the re matching of deductible structure, payout ratio, and medication coverage boundaries is worth considering.
The real threshold: claims settlement and trust building
Product adaptation is just the foundation. Making it understandable and trustworthy for users in the inclusive market is the key to reaching the "last mile" of insurance coverage; The trust of users is also an indicator of Internet channels to be improved. Yuanbao has also provided its own methodology for building user trust.
At the level of outreach, Yuanbao chooses to replace preaching with content: the exclusive sponsored documentary program "Hello, Emergency Doctor" conveys risk awareness and protection concepts through real emergency scenes, with over 1 billion exposures across the entire network; Using interesting science popularization columns to break down complex insurance terms and claims rules, making it easier for users to understand; Explore real claims stories, record the experiences of ordinary people fighting against diseases and being supported by insurance through documentary lenses, and convey the warmth of protection. At the claims level, the platform independently displays claims explanations and real claims data; Support for "one click upload" of materials, automatic recognition and classification of various medical bills uploaded by users, with medical insurance as fast as 34 minutes to close the case; The "Ruyi Compensation" service for difficult cases will help users receive an average compensation of 35000 yuan by 2025. Users can understand insurance in the content and confirm protection in claims. Trust is gradually accumulated through these concrete experiences.
Xu Xian stated at the press conference that insurance innovation needs to simultaneously respond to multiple needs such as people's livelihood security, enterprise operation, and industrial development, covering topics such as product design, sales and services, improvement of business capabilities, and social risk governance. The case of Yuanbao also verified this logic: the long-term sustainability of Internet insurance depends not only on the front-end sales ability, but also on the long-term investment in service system, claim settlement efficiency and user trust.
Continuous evolution:
From healthcare professionals to addressing the needs of people with illnesses
The records in the book end in 2025, and Yuanbao provided updated practical references in 2026.
In 2026, Yuanbao will continue to upgrade its products and services. On the product side, Yuanbao has upgraded its universal medical insurance to achieve full liability with zero deductible. After social security settlement, 100% of the liability will be compensated, providing one-stop coverage for "good doctors, good medicines, and good rehabilitation"; And launched medical insurance and critical illness insurance, responding to the protection needs of over 400 million patients by waiving health notifications and compensating for general past illnesses within the scope of responsibility. On the claims side, Yuanbao relies on AI technology to upgrade its claims services and launch the "Intelligent Compensation Assistance" function to assist cooperative insurance companies in conducting preliminary evaluations of small and low-risk cases, improve insurance company claims efficiency, and optimize user claims experience. As of June 2026, the settlement time for small claims under 10000 yuan has been shortened by 41%; Launch "claims recovery" to proactively follow up and assist users who give up claims midway to complete their applications. To broaden the scope of protection and shorten the waiting time for claims, this is the new solution for Yuanbao to deepen universal coverage in 2026.
The era proposition that Zhou Yanli proposed in the preface is that the insurance industry must answer: how to move from "risk screening" to "risk management", from "post compensation" to "full cycle governance", and from "commercial financial instruments" to "social governance hubs". This is not so much a proposition for a single company, but rather a common test for the entire industry in the new cycle of high-quality development. Whether the practice of Yuanbao can be replicated still requires time and data verification; But its inclusion in the academic perspective itself indicates that in the next stage of universal health insurance, the competition will not only be about price and scale.